
Comparing business loan matching marketplaces and banking platforms risks confusion when features, integrations, and lending access vary widely between providers. Many platforms restrict eligibility to certain regions, add technical barriers for small business owners, or limit feature access unless you commit to enterprise agreements. You can match a Mercury alternative to your business needs based on eligibility, technical fit, feature coverage, and lending workflow.
Table of Contents
Lending Gurus
At a Glance
The vendor advertises fast decision times, often within hours. Lending Gurus uses a conversational chat interface so you describe needs in plain language. The platform matches you with third-party lenders without any hard credit pulls and without requiring application forms.
Core Features
A conversational AI advisor named Guru analyzes your situation in real time and suggests lender matches. The marketplace covers a wide range of loan types and financial products and emphasizes transparent fees with no obligation to apply. Users keep their credit score intact during the matching process while offers arrive quickly.
Key Differentiator
The single feature that sets this marketplace apart is its AI-driven, conversation-first matching that connects people to suitable lenders instantly and without paperwork.
Pros
The chat approach reduces form fatigue and makes comparing options faster for busy business owners. Because matching uses no hard credit checks, you can explore lenders without risking your score. The platform reports quick turnaround on responses, and the fee model places no charge on you; lending partners pay commissions when funding closes.
Cons
- Limited to US users, so the service is not available to international applicants.
Who It’s For
You should consider Lending Gurus if you run a small business or manage personal debt and want a quick, low-friction way to surface loan options. The platform fits people who prefer conversational guidance instead of long forms. It also suits applicants whose credit profiles fluctuate and who want to shop offers without multiple credit inquiries.
Unique Value Proposition
Free to use and form free, the marketplace lets you compare lender options privately because lenders pay commissions on successful funding. That arrangement removes upfront cost and reduces sales pressure during early shopping. The workflow saves you time by turning a multi-form process into a single chat interaction.
Real World Use Case
A small business owner types growth needs into the chat and describes monthly revenue and desired loan size. Guru evaluates the details and returns several lender matches without pulling credit. The owner reviews options, selects a lender, and proceeds to the lender’s application with no obligation from the marketplace.
Pricing
Free to use. Lending Partners pay commissions upon successful funding. There is no fee to you and no obligation to proceed with any matched offer.
Website: https://lendinggurus.com
Grasshopper Bank
At a Glance
Backed by the FDIC and the full faith of the U.S. Government, Grasshopper Bank targets startups, fintechs, and small businesses. The bank pairs business checking accounts with high APY and cash back rewards for operating accounts. It also exposes embedded finance APIs so platforms can move money and accept payments programmatically.
Core Features
Grasshopper Bank offers FDIC insured business checking with competitive APY and cash back on transactions, plus lending options that include SBA and term loans. The platform provides embedded finance APIs for partner platforms and API banking for fintech use cases, alongside AI driven bookkeeping and cash management automation. Digital tools cover payments, invoicing, and treasury style cash flow management with partnerships across banking technology providers.
Key Differentiator
Grasshopper Bank focuses on embedded finance and fintech automation integrated with scalable digital banking tools. That concentration makes it useful when you need banking capabilities exposed as APIs for a product or marketplace. The vendor positions this as a single partner for deposits, movement of funds, and programmatic payment flows.
Pros
The platform delivers a modern, primarily digital banking experience tailored for small business needs and startup growth. Competitive APY and cash back rewards keep operating cash working harder in deposit accounts. The bank emphasizes embedded finance, so fintechs can link accounts and payment flows to customer experiences without managing custody infrastructure. Customer support and technology receive industry recognition, and the platform scales from small company banking to treasury style services.
Cons
-
Some advanced features and integrations require technical knowledge. Non technical teams will face a learning curve when using the APIs.
-
Physical branch access is limited because the bank is primarily digital. Businesses that need in person service may find the model restrictive.
-
Certain enterprise or specialized services may carry higher fees. Specific fee details are not listed in the product data.
When It May Not Fit
If your organization relies on regular in person banking or branch services, a primarily digital provider will feel incomplete. Small business owners without technical resources will struggle to use the embedded finance APIs effectively. Firms that need transparent, published fee schedules may prefer a bank that lists detailed pricing publicly.
Notable Integrations
- API banking
- BaaS
- AI connections
- Mobile banking
Who It’s For
Grasshopper Bank fits tech savvy small business owners, startup founders, and fintech companies that must embed banking into product workflows. Choose it when you need programmatic control of accounts, payments, or customer deposits. Avoid it if you need frequent branch visits or minimal technical setup.
Real World Use Case
A tech startup uses Grasshopper Bank to run treasury operations for its platform. The team automates bookkeeping and reconciliations with the bank’s AI driven tools while using embedded finance APIs to route customer payments. Lending options cover working capital when growth accelerates, keeping cash management centralized under one banking partner.
Website: https://grasshopper.bank
UnPay
At a Glance
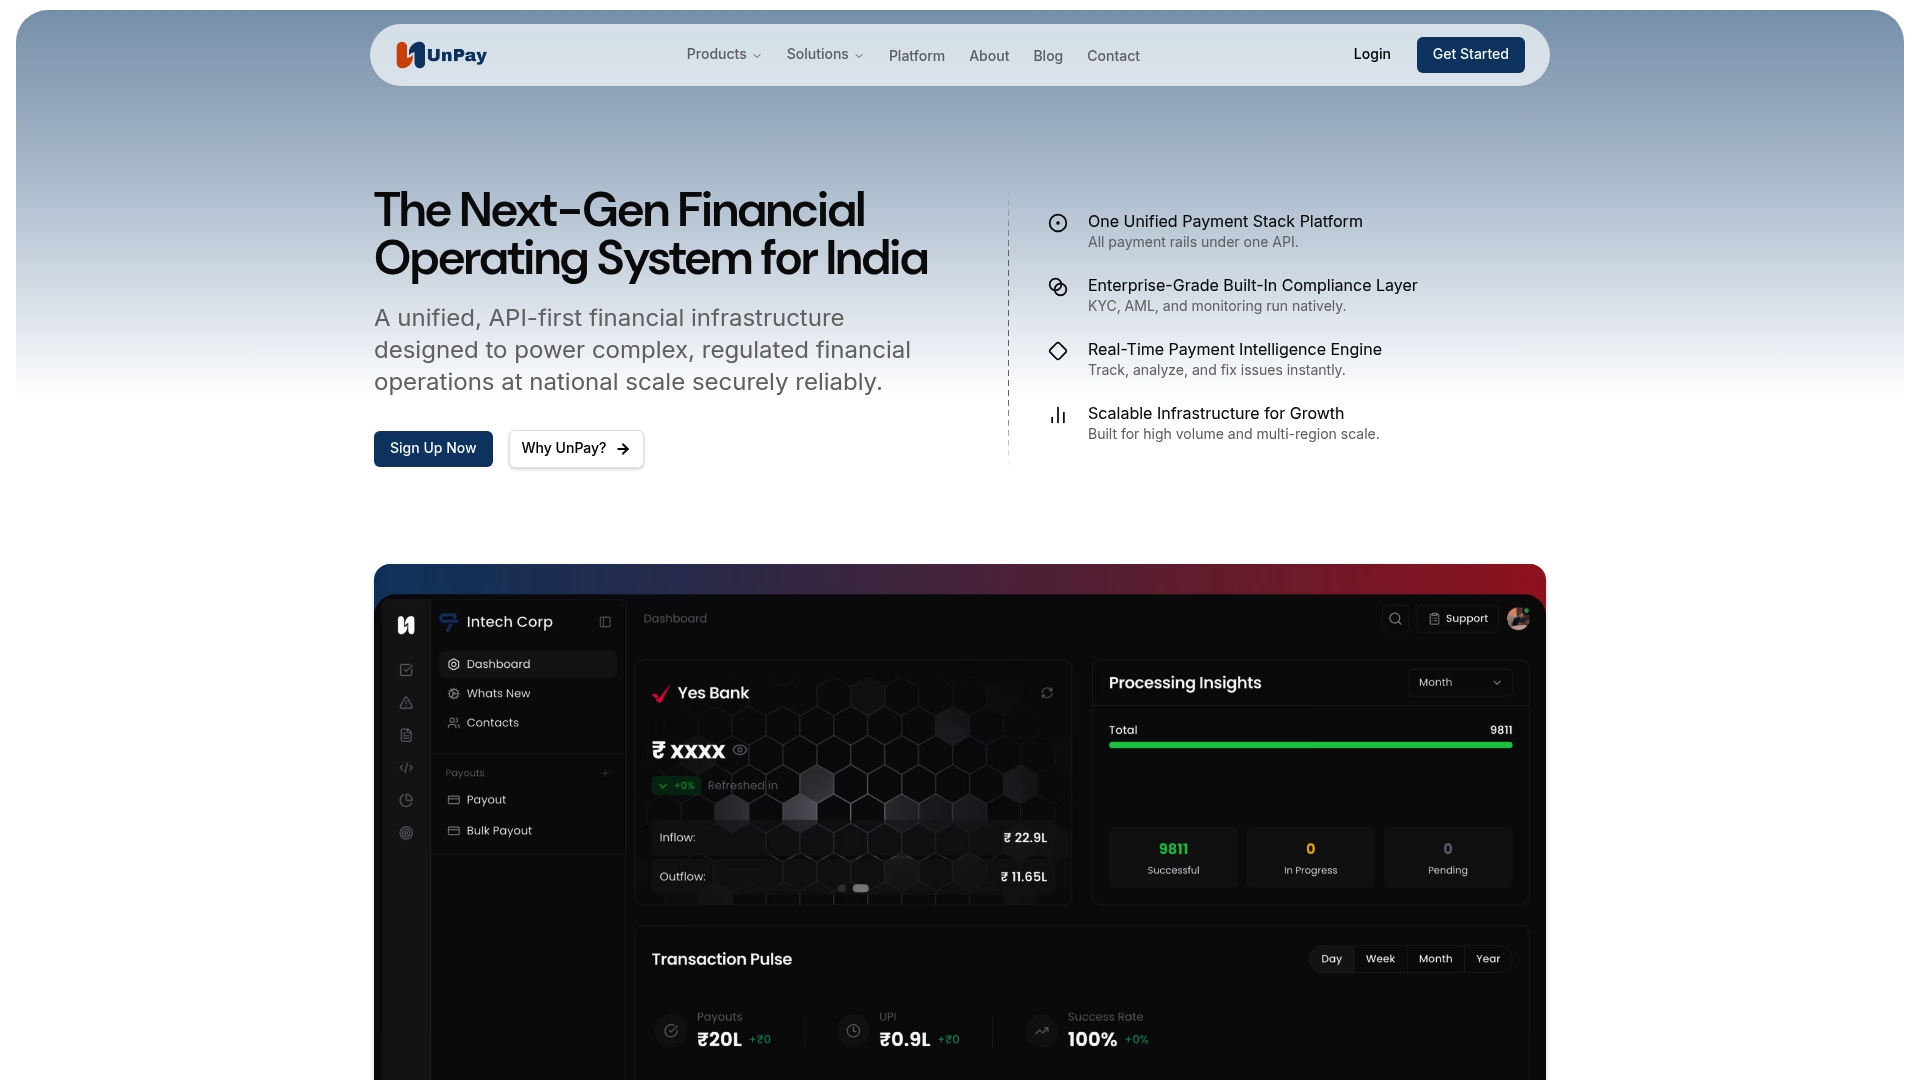
A single API covers payments, banking, lending, and escrow for enterprise operations across India. The platform bundles KYC, AML, and monitoring into the same developer surface. That design targets firms that need regulated financial workflows at national scale.
Core Features
UnPay exposes a unified API for all payment rails and provides SDKs and webhooks for integration. The system includes a built in compliance layer for KYC and AML and a real time analytics and monitoring engine for transaction visibility. The backend uses microservices based, event driven architecture to support high volume, multi region deployments and scalable banking and lending flows.
Key Differentiator
The platform consolidates multiple financial services into one API first operating system for regulated finance. That consolidation reduces the need to stitch separate vendors for payments, escrow, reconciliation, and lending. The single surface model is aimed at teams building large scale, regulated products in India.
Pros
UnPay reduces vendor fragmentation by combining payments, banking, and lending into a single platform, which simplifies integration points for engineering teams. The product emphasizes enterprise grade security and built in compliance controls for KYC, AML, and ongoing monitoring. Developer oriented SDKs and webhooks speed automation and let engineering teams embed reconciliation and escrow logic into existing stacks.
Cons
- Requires significant technical expertise for integration and ongoing maintenance, which raises internal development costs.
- Pricing is not publicly listed and appears tailored for enterprise contracts, so total cost is unclear for smaller buyers.
- The platform’s breadth and feature set can overwhelm small businesses without a dedicated technical or compliance team.
When It May Not Fit
If your business lacks an engineering team or a compliance lead, the integration effort will likely be costly and slow. Startups seeking inexpensive, plug and play payment solutions may find the product too complex. Companies that operate primarily outside India will need to confirm local banking rails and partnerships before committing.
Notable Integrations
- Multiple banking partners via API for clearing and settlement.
- Dev SDKs for popular programming languages to simplify implementation.
- Webhooks for real time updates on transactions and reconciliation events.
Who It’s For
Large financial institutions, fintech startups, and enterprises that need integrated, scalable, and compliant financial infrastructure in India. Teams that manage lending, escrow, or high volume payment flows will extract the most value. Organizations with internal engineering and compliance resources will move fastest.
Real World Use Case
An e commerce platform integrates UnPay to handle gateway routing, managed escrow for marketplace sellers, and real time transaction reconciliation. The platform reduces failed settlement investigations by centralizing logs and monitoring. That setup keeps regulatory checks in one place while the product team focuses on checkout experience.
Pricing
Pricing is not specified publicly and appears to follow an enterprise model with custom quotes per client. Expect quotes to reflect integration scope, transaction volume, and compliance features requested.
Website: https://unpay.co
Bluevine
At a Glance
Bluevine reports FDIC insurance up to $3 million through a pass through sweep network of partner banks. The company combines business checking, lending, and payment tools in one platform. Reviewers and awards frequently cited its ease of use and business focus.
Core Features
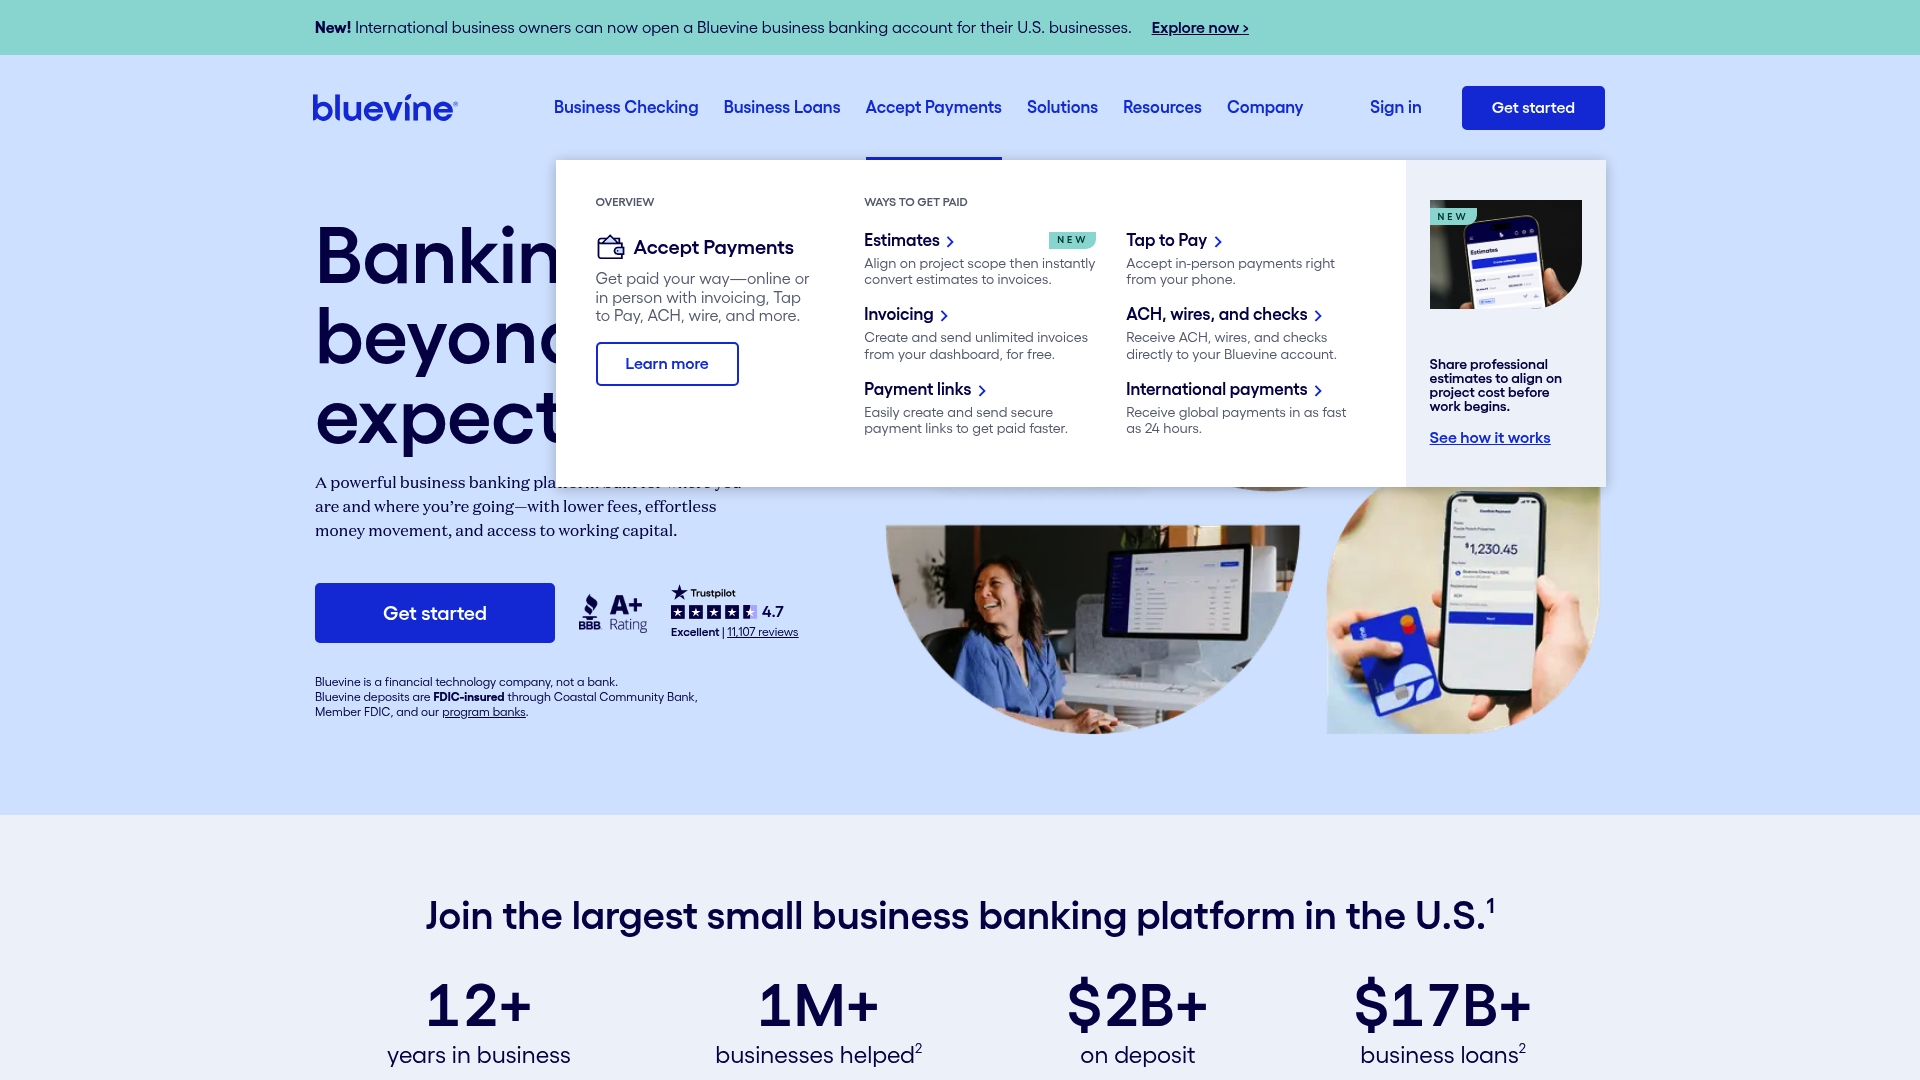
Business checking includes no monthly fees, high yield options on upgraded plans, bill pay, and sub accounts for budgeting. The platform issues physical and virtual debit cards with team spending controls and accepts payments by invoicing, Tap to Pay, ACH, wires, and secure payment links. Lending covers lines of credit up to $250K, term loans up to $500K, and SBA loans up to $350K.
Key Differentiator
The pass through sweep network that increases FDIC coverage above standard limits sets Bluevine apart for businesses holding larger balances. That coverage can reduce the need to split deposits across multiple banks. For companies that keep elevated cash balances, the deposit protection is the single most practical benefit.
Pros
Bluevine bundles checking, lending, and payment acceptance in one account, which simplifies cash management for small teams. The deposit coverage above standard FDIC limits reduces operational friction for businesses that store larger cash reserves. Bluevine reports a 4.7 out of 5 Trustpilot rating based on over 11,000 reviews, which the company highlights when discussing customer satisfaction. The platform also advertises awards from outlets such as CNBC and Forbes, reinforcing its market recognition.
Cons
- Reliance on third party banks for deposit insurance means administrative details can vary by partner bank and account type.
- Several features are limited to U.S. customers, so international teams will not get full functionality.
- International payments and wire transfers may incur extra fees that raise the effective cost of cross border transactions.
When It May Not Fit
If your business operates primarily outside the United States, several features will be restricted or unavailable. Companies that need a full-service commercial bank with in branch support and legacy services may find Bluevine too digitally focused. If avoiding any partner bank dependencies is a requirement, this model will not match that constraint.
Who It’s For
Small and medium sized business owners, freelancers, and startups that want a single platform for checking, payments, and growth capital. Owners who keep larger deposit balances and value higher deposit protection will benefit most. Teams that prefer a digital first banking experience and fast loan access will find the fit attractive.
Real World Use Case
A small retail shop keeps operating cash and reserves in Bluevine checking to earn a competitive rate. The owner automates monthly vendor payments using bill pay and sub accounts for inventory and payroll. When a seasonal inventory spike arrives, the shop draws on a short term line of credit to buy stock quickly.
Pricing
Standard business checking has no monthly fee and serves as the baseline plan. Premium plans add higher yield on balances and other discounts, with fees and eligibility listed on Bluevine’s site.
Website: https://bluevine.com
Comparison of alternatives
Lending Gurus enables users to rapidly find suitable lenders using an AI-powered, conversational chat interface, making it unique in avoiding traditional application forms. This analysis reviews how Lending Gurus compares to Grasshopper Bank, UnPay, and Bluevine to provide insight into these alternatives.
Streamlined Loan Matching
Lending Gurus simplifies loan discovery through its conversational AI, allowing users to avoid lengthy forms and focus directly on tailored lending options. In contrast, competitors like Grasshopper Bank focus on banking tools and integration features, while UnPay and Bluevine emphasize technical APIs and elevated FDIC insurance coverage. For applicants prioritizing a frictionless experience, Lending Gurus offers efficiency.
Technical and Financial Integration
Grasshopper Bank stands out for its embedded finance APIs, which support programmatic control of accounts for tech-savvy business operations. Similarly, UnPay consolidates payment, banking, and compliance workflows into a single API layer aimed at enterprise use cases within India. Both platforms outperform Lending Gurus when technical scalability is more critical than immediate loan comparison.
Best fit
- If you value quickly matching loans without traditional forms, Lending Gurus is well-suited to deliver efficiency and transparency.
- Firms needing programmatic banking capabilities should consider Grasshopper Bank for its API-driven services tailored to startups and fintechs.
- Organizations requiring national financial workflows and compliance modules may find UnPay’s unified API system advantageous within India.
- Small businesses managing significant reserves could turn to Bluevine for extended FDIC deposit protection and bundled banking tools.
Our pick
Lending Gurus excels for users seeking a conversational and frictionless approach to discovering lending options. Its AI-driven guidance and no hard credit inquiry policy provide streamlined matching uniquely tailored to applicants seeking immediacy with reduced paperwork. However, businesses pursuing technical integrations, elevated deposit management, or international scalability may benefit from exploring alternative platforms specializing in those areas.
This comparison evaluates loan matching marketplaces to support varied business needs efficiently and effectively.
| Platform | Core Feature | Notable Advantage | Best For | Pricing | Limitation |
|---|---|---|---|---|---|
| Lendinggurus | Conversational AI for lender matching | No credit score impact during matching | Small businesses, personal debt management | Free to use | Limited to US users |
| Grasshopper Bank | Embedded finance APIs | High APY and cash back on business accounts | Tech-savvy small business owners, fintechs | Price not published | Limited physical branch access |
| UnPay | Unified API for payments and banking | Comprehensive compliance controls (KYC/AML) | Large-scale financial institutions, fintechs | Price not published | High technical requirements for implementation |
| Bluevine | Business checking and lending integration | High FDIC insurance coverage through sweep network | SMBs requiring high deposit protection | Free for standard checking | Limited features for international businesses |
What Are Key Considerations When Choosing Mercury Alternatives?
Finding the right financial platform means avoiding long applications and credit score hits. Lendinggurus delivers a fast way to connect you with lenders through a conversational AI advisor named Guru. You can describe your needs in plain language and receive personalized matches without any hard credit pulls or paperwork.
This makes Lendinggurus an excellent option for small business owners and individuals who want a simple process, quick responses, and no upfront fees. Compare your options efficiently and decide with confidence by visiting Lendinggurus. Start by sharing your funding needs and review relevant lender matches in minutes.
Get matched with lenders now at Lendinggurus
FAQ
What features make Lendinggurus a preferred choice for quick loan matching?
Lendinggurus excels in fast decision times, often within hours, and employs a conversational chat interface to match customers with suitable lenders. The platform allows users to describe their needs in plain language without hard credit pulls, making it easy to explore loan options. You can quickly and privately assess your lending possibilities without the typical paperwork.
How does Lendinggurus compare to Grasshopper Bank in terms of banking features?
Grasshopper Bank offers a suite of features that focus on embedded finance and API banking for tech-savvy startups, which is beneficial for firms needing banking solutions integrated into product workflows. Lendinggurus, on the other hand, focuses on matching users with lenders quickly and without paperwork, making it more suitable for users seeking immediate loan options without a strong emphasis on banking integration. This allows you to access loans swiftly while keeping your credit score intact.
Can users expect to maintain their credit score while using Lendinggurus?
Yes, users can maintain their credit score while exploring options on Lendinggurus. The platform does not conduct hard credit pulls during its matching process, allowing you to assess various lenders without impacting your credit profile. This feature provides a low-commitment way to gather loan offers effectively.
What types of loans can users find on Lendinggurus?
Lendinggurus features a variety of loan types and financial products by connecting users to third-party lenders. The marketplace emphasizes transparent fees and offers, allowing users to find options that fit their specific financial situations. You should expect quick feedback on potential matches to meet your needs without the hassle of traditional applications.
How do users benefit from the commission structure of Lendinggurus?
Lendinggurus operates on a commission-based model where lending partners pay commissions upon successful funding. This means users can explore loan options free of charge, making it an appealing choice for those hesitant to commit to upfront costs. This approach minimizes pressure during the initial phase of assessing lending opportunities.
