
A working capital loan gives you a lump sum you repay on a fixed schedule, built for a defined, one-time expense. A line of credit is revolving funding you draw as needed and repay to restore your limit, built for recurring or unpredictable cash gaps. Pick the loan for a specific project with a known cost. Pick the line of credit for payroll timing, seasonal inventory, or gaps you can’t fully predict.
Table of Contents
- Working Capital Vs Line Of Credit: What Each Term Actually Means
- How Does Each Financing Option Actually Work?
- Working Capital Loan Vs Line Of Credit: Side-By-Side Comparison
- What Are the Pros and Cons of Each Option?
- How Much Do These Options Cost and How Fast Can You Get Funded?
- Who Qualifies and What Do Lenders Ask For?
- When Should You Use a Working Capital Loan Instead of a Line of Credit?
- What Risks Should You Watch For With Short-Term Financing?
- How Do You Apply and What Should You Ask Lenders First?
- A Practical Take on Choosing Between These Two Products
- Compare Financing Offers Without the Guesswork of Cold Calls
- Where to Learn More About Working Capital and Lending Options
- Sources
Working Capital Vs Line Of Credit: What Each Term Actually Means
A working capital loan is lump-sum term financing. You borrow a fixed amount, get it deposited at once, and pay it back on a set schedule, usually with fixed payments over a defined term. It behaves like most business loans you’ve heard of.
A line of credit works differently. A lender approves you for a maximum limit, and you draw only what you need. You pay interest on the drawn balance, not the full limit, and once you repay a draw, that capacity becomes available again. According to Fora Financial’s comparison of the two products, this revolving structure is the core distinction that shapes everything else, from cost to flexibility.
Before you talk to any lender, know your actual working capital position:
Working capital = current assets − current liabilities
If that number is thin or negative, you have a cash flow problem a line of credit can smooth over. If you’re funding a specific purchase, a term loan usually fits better.
Common uses break down predictably:
- Payroll and rent — recurring, variable, best matched to a line of credit
- Inventory before a busy season — cyclical, often a line of credit
- One-off equipment or buildout costs — defined, best matched to a working capital loan
Consumer protection resources like the FTC’s credit and loans guidance, along with registries such as NMLS Consumer Access and FINRA, exist to help you verify a lender’s legitimacy before you sign anything.
How Does Each Financing Option Actually Work?
A working capital loan follows a simple path:
- You apply and submit financial documents.
- The lender approves a fixed amount and disburses it as a single lump sum.
- You make scheduled payments, usually monthly, until the loan is paid off.
- The loan closes. There’s no renewal, no ongoing relationship, unless you apply again.
A line of credit follows a different rhythm:
- The lender approves a maximum limit based on your revenue and financials.
- You draw funds as needed, up to that limit.
- You repay what you drew, and your available limit restores.
- The line renews periodically, and the lender reviews it, sometimes annually.
The interest math matters here. On a working capital loan, interest accrues on the full principal from day one. On a line of credit, you only pay interest on what you’ve actually drawn, according to Investopedia’s breakdown of how lines of credit work.
Pro Tip: Don’t treat a line of credit as permanent revenue. Banks often structure these as demand loans, meaning they can reduce your limit or ask for repayment even if you’ve never missed a payment, as BDC explains in its comparison of the two structures.
Say you need $20,000 for a defined marketing push. A loan gives you all $20,000 upfront and locks in your payment. A line of credit lets you draw $8,000 now, $5,000 next month, and hold the rest in reserve. Same need, very different cash flow pictures.

Working Capital Loan Vs Line Of Credit: Side-By-Side Comparison
| Dimension | Working Capital Loan | Line Of Credit |
|---|---|---|
| Best for | One-time, defined expenses | Recurring or unpredictable cash gaps |
| Repayment structure | Fixed installments over a set term | Flexible, tied to what you draw |
| Flexibility | Lump sum, no revolving access | Revolving, draw and repay repeatedly |
| Interest and fees | Accrues on full principal | Accrues only on drawn balance |
| Collateral | Sometimes required, varies by lender | Often unsecured for smaller limits, secured for larger ones |
| Borrowing limit | Set by projected use and financial history | Set by revenue, cash flow, and credit history |
| Funding speed | Varies by lender type | Often faster once approved; draws are near-instant |
| Renewal risk | None, loan simply closes | Subject to periodic review and possible reduction |
Three quick takeaways:
- If your expense has a fixed dollar amount and end date, a loan gives you payment predictability.
- If your need shifts month to month, a line gives you access without paying for money you’re not using.
- Either product can get pulled back if your financials weaken, so read the fine print on renewal terms either way.
What Are the Pros and Cons of Each Option?
Working capital loan pros:
- Predictable, fixed payments make budgeting simple
- No risk of a lender reducing your access mid-term
- Often better for larger, one-time capital needs
Working capital loan cons:
- You pay interest on the full amount, even if you don’t need all of it right away
- Less flexible once funded — you can’t adjust the amount
Line of credit pros:
- Only pay interest on what you actually draw
- Available on demand for irregular timing gaps
- Reusable without reapplying each time
Line of credit cons:
- Lenders can reduce or call the line during renewal, particularly at banks
- Variable rates can make total cost harder to predict
Lines of credit function best as a short-term liquidity cushion, not a permanent funding source. Because lenders retain the ability to modify or revoke them, businesses that lean on a line for core operating cash without a fallback plan are exposed if that access shrinks.
Skip trying to compare APRs in isolation. Run the same dollar need through both products and compare total cost across a realistic repayment timeline instead.
How Much Do These Options Cost and How Fast Can You Get Funded?
Cost depends on more than the headline rate. Watch for:
- Interest type — fixed for loans, often variable for lines
- Origination fees — charged upfront on many loans
- Draw fees — some lines charge each time you tap funds
- Maintenance fees — annual or monthly charges just to keep a line open
Traditional banks tend to offer lower rates but ask for stronger credit history, more documentation, and sometimes collateral. Fintech lenders move faster and often underwrite on cash flow and bank statements rather than credit score alone, but that speed usually comes at a higher cost, according to Drip Capital’s look at alternative financing options.
Pro Tip: Before comparing offers, build a simple checklist: total principal, all fees, how often you’ll draw, and how many days the balance will realistically stay outstanding. That number tells you more than any advertised rate.
Who Qualifies and What Do Lenders Ask For?
Lenders typically look at:
- Monthly revenue and recent bank statements
- Time in business, often two years or more for the best terms
- Tax returns and business registration documents
- A personal guarantee, especially for newer or smaller businesses
Credit score matters, but it’s rarely the deciding factor. Lenders weigh monthly revenue and cash flow more heavily than a single score. Secured options, where you pledge collateral, often unlock larger amounts or better pricing than unsecured products, but not every business needs to go that route.
When Should You Use a Working Capital Loan Instead of a Line of Credit?
- Payroll gap during a slow month — Line of credit. The need is recurring and hard to predict exactly.
- Seasonal inventory buildup before peak season — Line of credit. Demand shifts year to year, and a revolving limit lets you scale draws to actual need. A horticulture retailer financing new grow equipment faces the same seasonal timing pressure.
- One-time marketing campaign with a fixed budget — Working capital loan. You know the exact cost and timeline.
- Equipment purchase — Working capital loan, or equipment-specific financing. The cost is defined and the asset has a clear useful life.
- Invoice timing mismatch — Line of credit. You’re bridging a temporary gap between billing and payment, not funding a permanent cost increase.
The deciding factor is almost always the same: defined cost points toward a loan, recurring or variable need points toward a line. Many businesses use both. A line handles the day-to-day gaps while a term loan covers a bigger, one-time investment.
What Risks Should You Watch For With Short-Term Financing?
Common pitfalls include:
- Borrowing more than your cash flow can comfortably repay
- Getting your line reduced or called during a renewal review
- Stacking multiple fees across draws, maintenance, and renewals
- Taking on a repayment schedule that outpaces your actual revenue timing
Pro Tip: Keep a cash buffer, model your worst-case repayment scenario before you draw, and keep your bank statements and tax documents current so you’re never scrambling when a lender asks for updated financials.
Run this checklist before applying: What’s your projected cash flow over the repayment period? How fast can you realistically repay? What’s your fallback if revenue dips mid-term?
How Do You Apply and What Should You Ask Lenders First?
Application checklist:
- Gather recent bank statements, tax returns, and business registration documents
- Know whether a lender will do a soft pull or a hard pull before you apply, per FTC guidance on credit and loans
- Have a clear number in mind for how much you need and why
Questions to ask before signing:
- What fees apply beyond the interest rate, including draw or maintenance fees?
- Is this a demand loan the lender can call at any time?
- What triggers default, and what happens if it’s triggered?
- How long does funding actually take once approved?
Lending Gurus matches you to vetted lending partners through Guru, a free conversational tool. Partners decide approval, rates, and terms. There’s no guarantee of approval or amount.
A Practical Take on Choosing Between These Two Products
Most small businesses overthink this decision. The expense itself tells you almost everything: if it’s one-time and has a fixed cost, a working capital loan gives you payment certainty. If it’s ongoing or unpredictable, a line of credit keeps you from paying for capital you don’t need yet.
If you want to compare real offers instead of guessing, Guru from Lending Gurus can match you with vetted partners in minutes. Partners set the actual terms and rates, not us.
Compare Financing Offers Without the Guesswork of Cold Calls
Calling five lenders and filling out five applications wastes time you don’t have when payroll is due Friday. Guru, the free conversational tool from Lending Gurus, asks about your business once and matches you to vetted lending partners in minutes, without a hard credit pull.
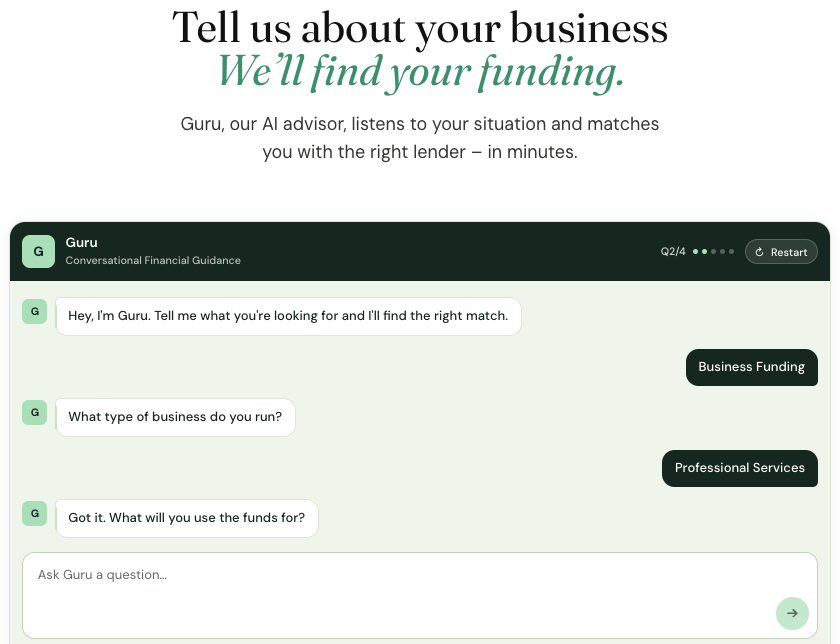
Whether you’re leaning toward a working capital loan or a revolving line, Guru surfaces partners suited to your situation, your monthly revenue, and your time in business. Lending Gurus is a matching platform, not a lender. Partners decide approvals, rates, and terms, and nothing here promises a specific outcome. Full details on how the matching process works are outlined in Lending Gurus’ terms and conditions.
Ready to see what’s available? Visit Lending Gurus and start the conversation with Guru, or read how the matching process works before you begin.
Where to Learn More About Working Capital and Lending Options
- Fora Financial — clear definitions and practical comparisons between loans and lines
- BDC — detail on renewal terms and demand loan structure
- Investopedia — risk guidance on treating lines as short-term tools
- FTC — consumer protection basics before you apply
- Drip Capital — bank vs. fintech speed and cost tradeoffs
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
