
No, prequalification typically does not affect your credit score, because most lenders use a soft inquiry to run the check. Preapproval and formal applications work differently. They often trigger a hard inquiry, which can lower your score slightly for a short period.
Experian confirms that prequalification generally relies on a soft pull, while Capital One notes that submitting an actual application after a preapproval offer can lead to a hard pull. The CFPB adds that prequalification never guarantees final approval, since underwriting happens later.
Here’s what typically happens at each stage:
- Prequalification: soft inquiry, no score impact, quick eligibility snapshot
- Preapproval: sometimes soft, sometimes hard, depending on the lender and loan type
- Formal application: hard inquiry, can lower your score temporarily
Quick fact: Hard inquiries usually cost most people fewer than five points on a FICO score, and the effect fades within months. This guide walks through the mechanics, the timeline, the exceptions that catch people off guard, and what to do before you apply anywhere.
Table of Contents
- Prequalification vs. preapproval: what’s the real difference?
- How do soft and hard credit inquiries actually work?
- How much does a hard inquiry lower your score, and for how long?
- When can prequalification turn into a hard credit pull?
- What should you do before applying for a loan or credit card?
- Why the soft vs. hard distinction gets glossed over
- Explore lender matches without a hard pull upfront
- Frequently Asked Questions
- Sources
Prequalification vs. preapproval: what’s the real difference?
Prequalification is a quick, low-commitment check. You share basic details, like income range or estimated credit standing, and the lender gives you a rough sense of what you might qualify for. Most lenders run this with a soft inquiry, which means it won’t touch your score.
Preapproval goes deeper. Lenders often ask for documentation, pay stubs, tax returns, or bank statements, and verify what you told them. For mortgages and auto loans especially, this deeper look frequently includes a hard inquiry. Experian’s research draws this distinction clearly: prequalification for cards and personal loans usually stays soft, while preapproval for bigger-ticket loans tends to get more invasive.
Here’s the catch: not every lender uses these words the same way.
- Some call a soft-pull check “preapproval” instead of prequalification
- Others use “prequalified” for offers that actually require a hard pull once you respond
- Auto lenders and mortgage lenders are the most likely to blur these lines
Don’t assume based on the label alone. Ask the lender directly which type of inquiry applies to your situation before you hand over any information.
How do soft and hard credit inquiries actually work?
A soft inquiry happens when a lender or another party checks your credit without it affecting your score. Prequalification checks fall here, along with prescreened credit offers you get in the mail, and any time you check your own credit report. Soft inquiries show up only on the version of your report you see, not the one lenders pull.
A hard inquiry happens when you submit a formal application. Auto loan applications, mortgage applications, and most personal loan or credit card applications trigger this. Preapproval for a mortgage or auto loan, once a lender verifies your documents, often counts as hard too.
Hard inquiries are visible to every lender who pulls your report going forward, for as long as they stay listed.
Key number: Experian reports that hard inquiries knock off fewer than five points from most FICO scores. That’s a modest hit for most borrowers.
Scoring models also build in a workaround for people comparing offers. Mortgage and auto inquiries made within a short window typically get grouped as a single inquiry for scoring purposes, which is why rate-shopping for a home or car loan doesn’t punish you the way five separate credit card applications would.
How much does a hard inquiry lower your score, and for how long?
For most people, a single hard inquiry drops a FICO score by fewer than five points. Experian’s data puts that figure at the center of typical outcomes, though your specific results depend on your overall credit file.
Timing matters as much as the size of the dip. Hard inquiries stay on your credit report for two years, but they generally affect your FICO score for about a year. After that window, the inquiry is still visible to anyone reading your full report, but the scoring models stop factoring it in.
Two details worth flagging:
- Thin credit files feel it more. If you have a short credit history or few open accounts, a single hard inquiry can move your score by a larger relative amount than it would for someone with years of established credit.
- Established credit histories bounce back fast. A healthy, longstanding credit profile usually absorbs a hard inquiry with a smaller, shorter dip.
None of this means you should avoid credit checks altogether. It means timing them well matters more than avoiding them entirely.
When can prequalification turn into a hard credit pull?
Prequalification usually stays soft, but there are real exceptions worth knowing before you start.
- Loan type matters. Mortgage and auto lenders are more likely to run hard checks once you move past the initial estimate, even if they still call it “preapproval.”
- Your actions can trigger it. Submitting pay stubs, tax documents, or bank statements, or clicking “accept” on a preapproval offer, can convert a soft check into a hard one.
- Language varies by lender. One lender’s “preapproval” might mean something entirely different from another’s, especially in mortgage lending, where accurate preapproval amounts depend on how thoroughly the lender verified your finances.
Pro Tip: Before you submit anything, ask the lender directly: “Will this be a soft or hard inquiry?” Get the answer in writing if you can. A two-minute question can save you an unnecessary score dip.
What should you do before applying for a loan or credit card?
Start by confirming the inquiry type with every lender you’re considering. Don’t assume prequalification means soft just because it usually does.
- Use prequalification and prescreened offers first. They let you compare estimated terms without touching your score, so save formal applications for the lender that actually fits.
- Group rate-shopping into a short window. Mortgage and auto inquiries made close together are typically treated as one for scoring purposes.
- Pull your credit reports and fix errors. Checking your own report is a soft inquiry, and disputing mistakes before you apply can help your standing.
- Pay down balances and stay current. Lower utilization and on-time payments help your score hold steady heading into any hard pull.
- Try a soft-match option first. Lending Gurus uses a conversational tool called Guru to match you with vetted lending partners based on your situation, without a hard pull during that initial matching step.
Pro Tip: If a lender won’t clearly answer whether their check is soft or hard, treat that as a signal to keep shopping. Transparent lenders explain their process without hesitation.
Why the soft vs. hard distinction gets glossed over
Most articles on this topic treat “prequalification” and “preapproval” as if every lender defines them identically. They don’t. That inconsistency is the real reason so many people get surprised by a score dip they didn’t expect.
The bigger issue is that borrowers often stop asking questions the moment a lender says “no impact to your credit.” That phrase gets used loosely. It’s frequently true at the prequalification stage and frequently false the moment you move into documentation and verification. The five-point-or-less figure from Experian sounds small, and for most people it is. But if you’re already sitting on a thin file or a recent ding, stacking multiple hard pulls from different loan types in the same month is where people get burned, not from prequalification itself.
Lending Gurus was built around this exact gap. Guru asks about your situation and matches you to partners without running a hard pull during that initial step, which means you get to see your options before you commit to anything that could move your score. Lending Gurus doesn’t decide approvals or set terms. The lending partners do that. But the soft-match step means you’re not gambling your score just to find out what’s available.
Explore lender matches without a hard pull upfront
Shopping around for financing usually means filling out form after form and hoping the hard inquiries don’t stack up before you find the right fit. Lending Gurus takes a different first step: Guru asks about your situation directly and matches you to vetted lending partners without a hard credit pull during that initial matching process.
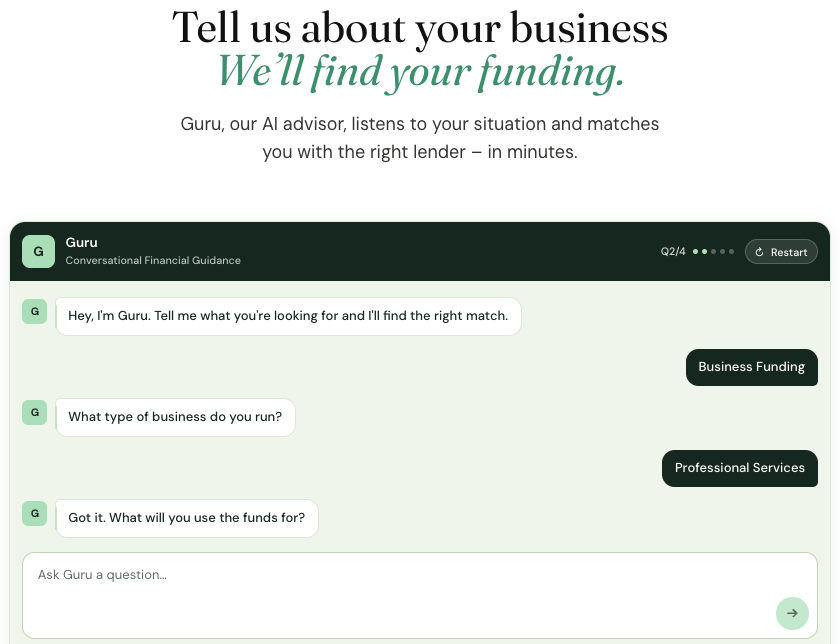
That means you can compare potential paths, working capital, lines of credit, equipment financing, debt consolidation, and more, before any formal application touches your credit. Lending Gurus is a referral platform, not a lender. The partners you get matched with make the actual decisions on approvals, rates, and terms, and nothing here is guaranteed. If you want to see what you might qualify for without committing your score to it, see how the matching process works or head to the Lending Gurus homepage to get started.
Frequently Asked Questions
Does prequalification affect credit score in most cases?
No. Most prequalification checks use a soft inquiry, which doesn’t show up on the credit report lenders see and doesn’t affect your score. The exception is when a lender’s “prequalification” process actually functions like a hard-pull preapproval, which is why confirming the inquiry type matters.
Does preapproval lower credit score?
It can. Preapproval for mortgages and auto loans often involves verifying documents, which frequently triggers a hard inquiry. That hard inquiry can lower your score by a few points, temporarily.
How does prequalification work if it doesn’t check my full credit?
Lenders typically ask for basic information, like estimated income or a general credit range, and run a soft pull to gauge whether you’d likely qualify. It’s a preliminary estimate, not a guarantee of approval, according to the CFPB.
What are the credit effects of prequalification versus a formal application?
Prequalification generally has no credit effect. A formal application almost always involves a hard inquiry, which can cost a few points and typically influences your FICO score for about 12 months, even though it stays on your report for two years.
Can multiple prequalification checks hurt my score if I compare several lenders?
Not usually. Since most prequalification checks are soft inquiries, comparing several lenders this way won’t stack up damage. This is different from submitting multiple formal applications, though mortgage and auto inquiries made in a short window are typically counted as one for scoring purposes.

This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
