
Comparing invoice financing rates, approval speed, and lender transparency is time-consuming for small and medium-sized business owners. Many single-lender platforms hide key terms, restrict offers by geography, or require multiple credit checks before showing choices. This comparison explains which invoice financing marketplace matches your location, approval needs, and risk profile without wasted effort.
Table of Contents
Lending Gurus
At a Glance
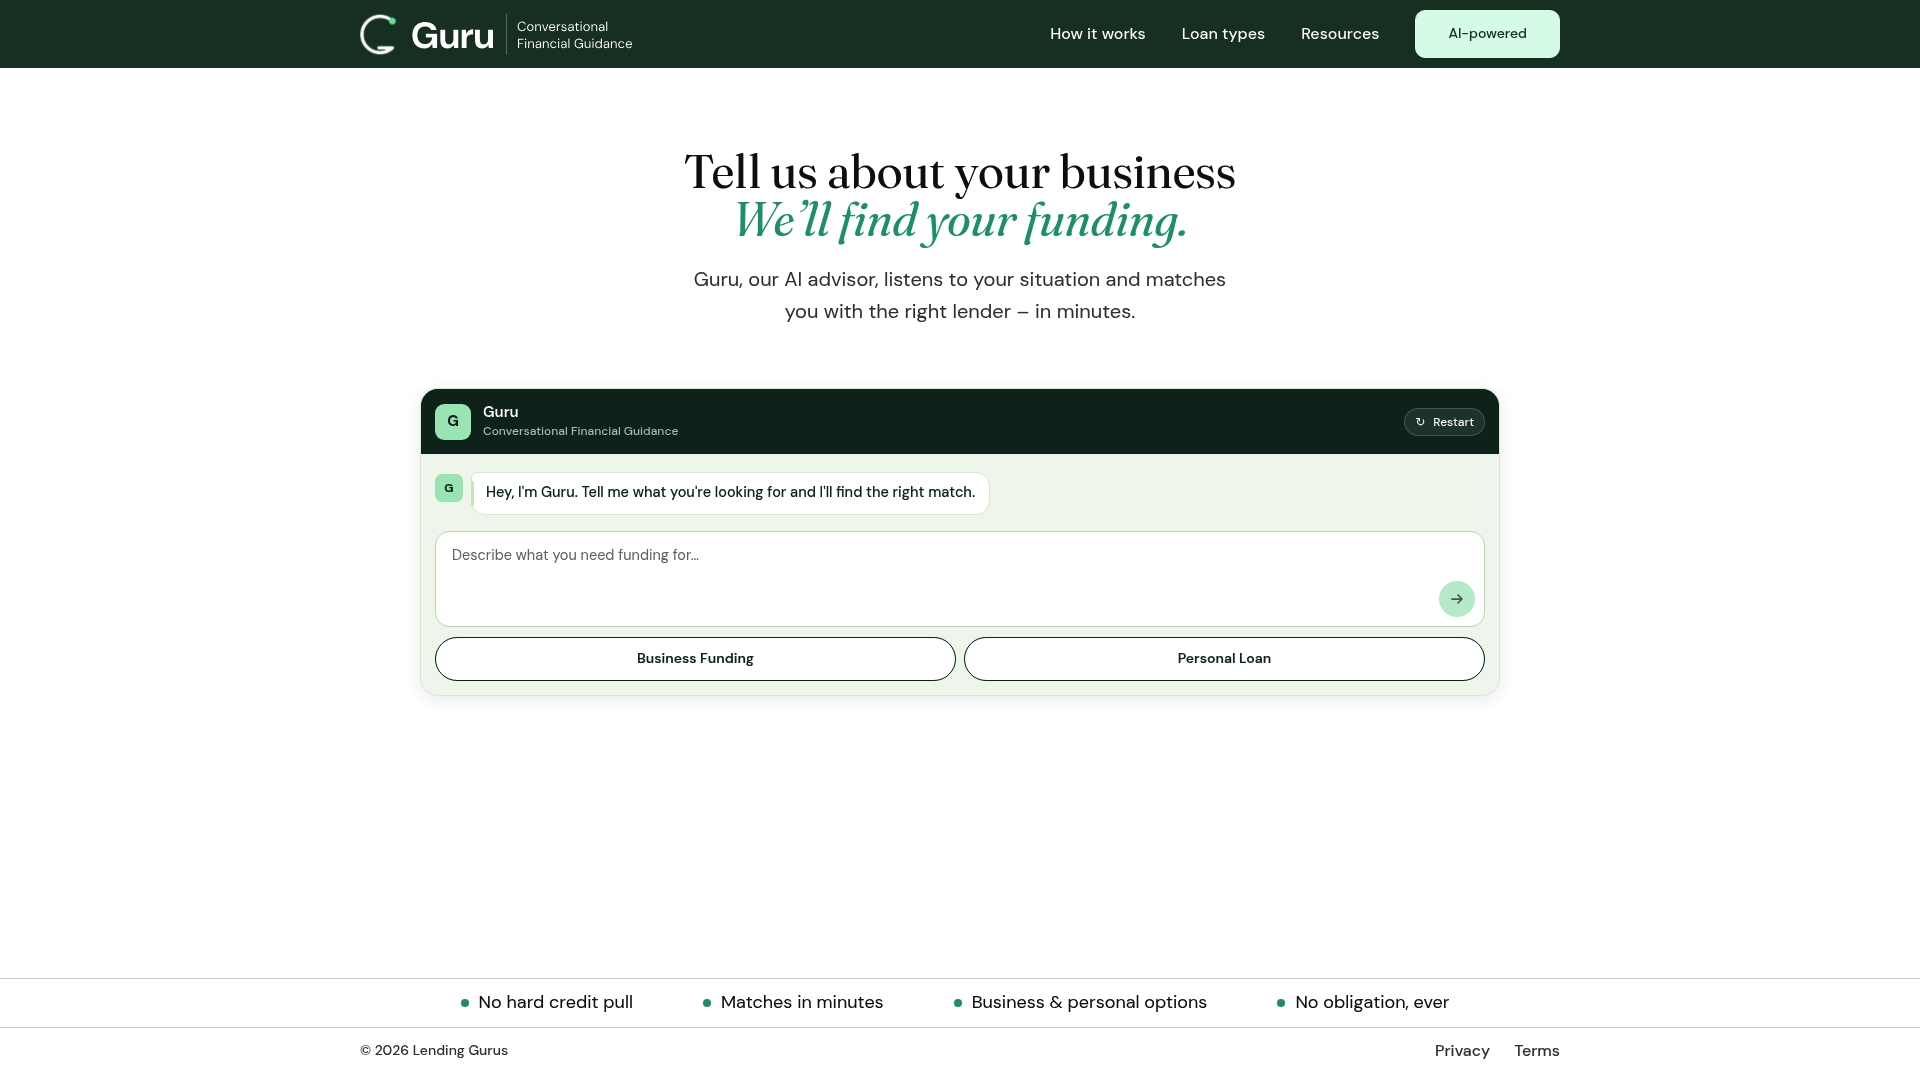
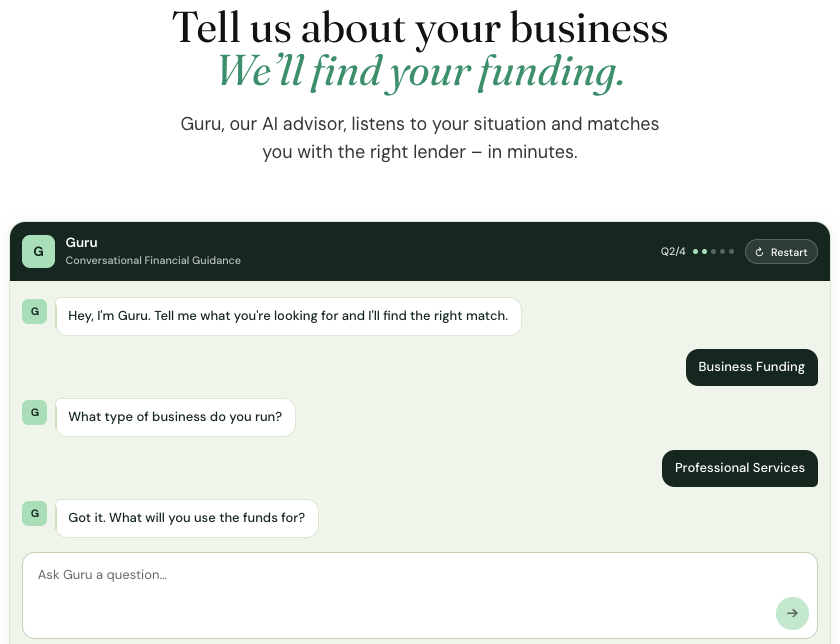
According to the company, the platform connects users with suitable lenders within minutes. The service uses an AI conversational advisor named Guru so you can describe your finances in plain language without filling out long forms. Matching requires no hard credit pull and carries no obligation to apply.
Core Features
The platform runs an AI match engine that asks conversational questions and builds a borrower profile. It then shows lender matches for business loans, personal loans, equipment financing, invoice funding, and real estate financing. Educational resources and transparent disclosure of how the site is paid are part of the experience.
Key Differentiator
The core difference is the conversational AI advisor workflow that captures context in chat and returns tailored lender matches without a hard credit inquiry. That approach removes form fatigue and preserves your credit score while producing lender options.
Pros
The conversational flow reduces form filling and speeds the initial screening so you spend less time explaining your needs. The platform lists a wide variety of loan types, which helps small business owners compare options for equipment, invoice funding, and real estate. Because matching does not use a hard credit pull, you can shop options without affecting your credit score. The service is free to users and the site discloses that lenders compensate the platform after matches or funded deals.
Cons
- Dependent on lender partner availability and terms.
Who It’s For
U.S.-based small business owners and entrepreneurs who want quick, personalized loan options without an immediate application. Individuals seeking debt consolidation or refinancing can use the conversational intake to see options before applying. People who prefer no-impact credit shopping will find the chat-first approach useful.
Unique Value Proposition
Guru listens to your situation in chat and produces lender matches without a hard credit inquiry. That means you can explore multiple loan categories without triggering credit checks. For a small business owner, this reduces the risk of multiple credit hits while you compare offers. For someone unsure which product they need, the conversational intake replaces technical forms with plain-language prompts.
Real World Use Case
A small business owner types a short description of cash flow needs into chat. Guru asks follow-up questions, builds a profile, and then surfaces lender matches that fit the business size and purpose. The owner reviews options without a hard credit pull and chooses which lenders to contact or ignore.
Pricing
The service is free to users. Lending Gurus is paid by lender partners when matches lead to funded loans, so there are no user fees or charges for browsing options.
Website: https://lendinggurus.com
Lendio
At a Glance
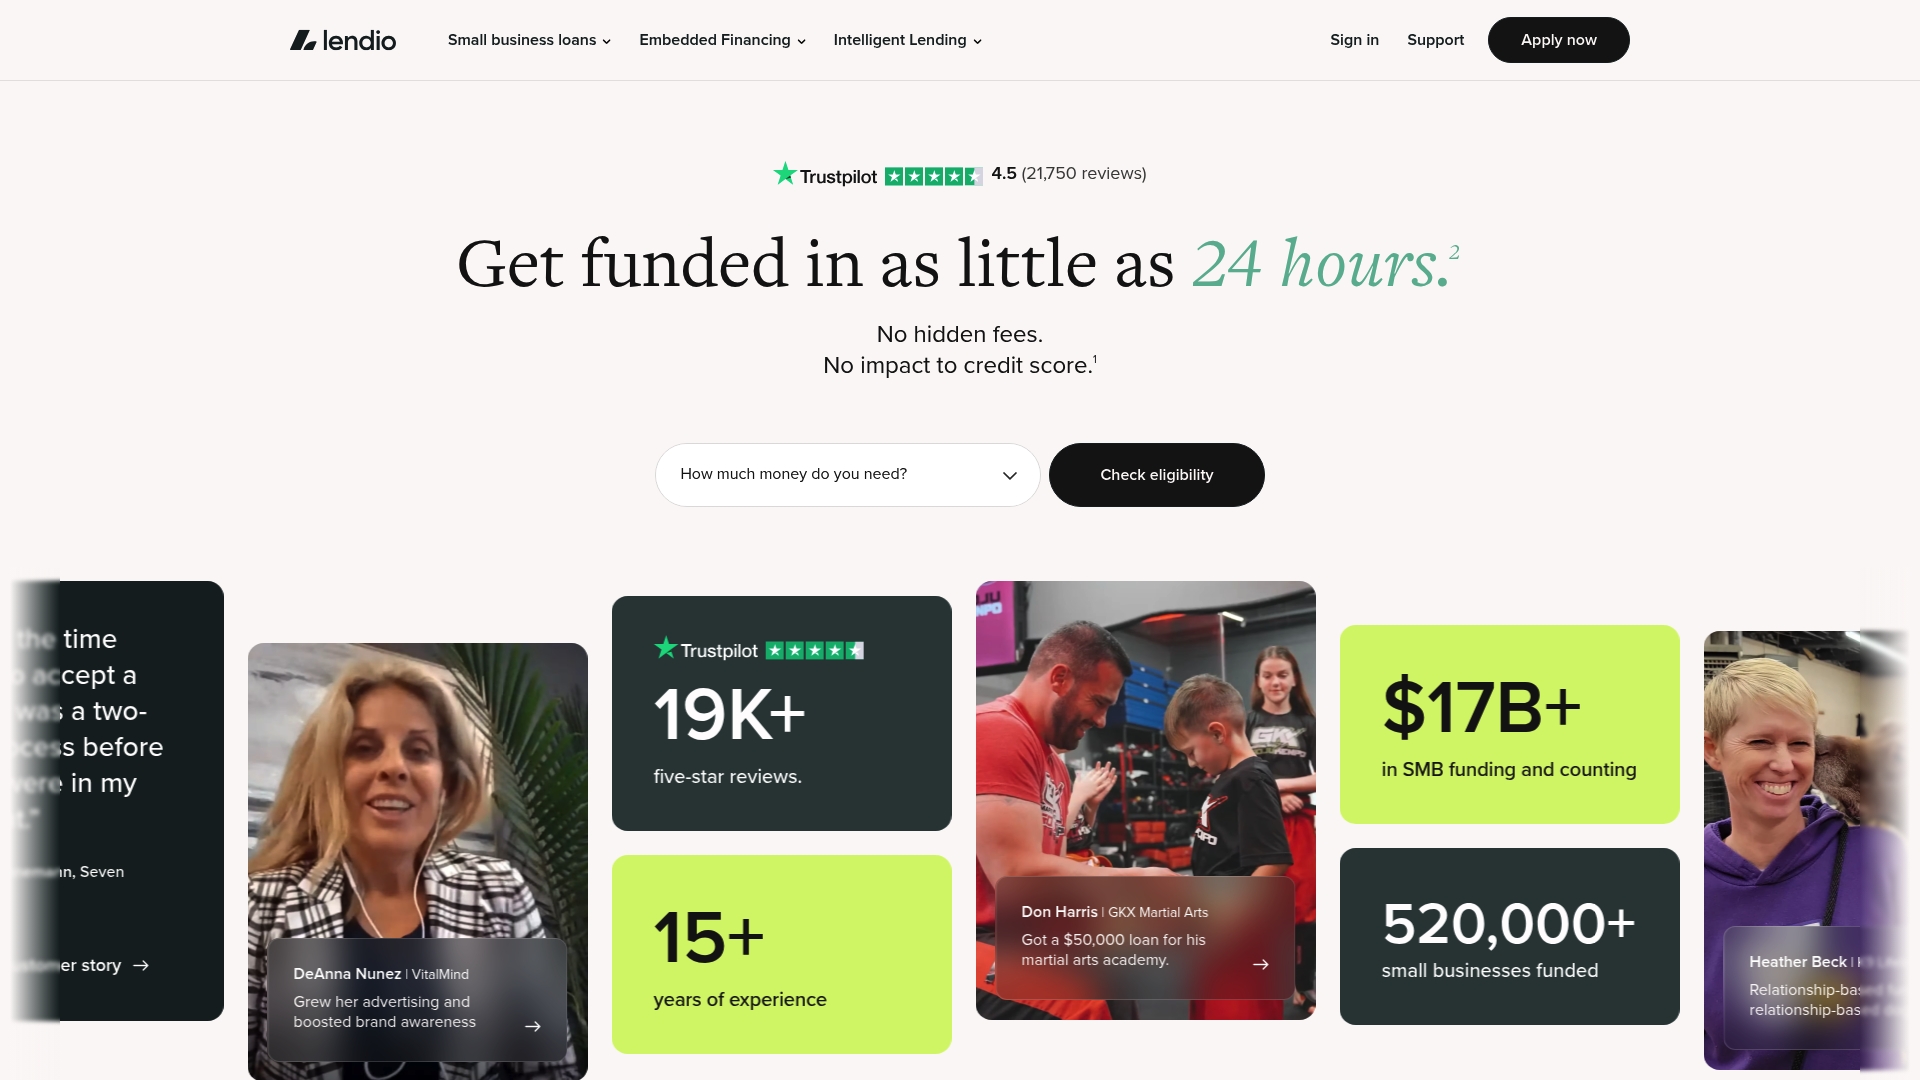
Lendio reports more than 21,000 Trustpilot reviews at a 4.6-star rating. The company says it links applicants to a marketplace of 75 vetted lenders and that funding can arrive in as little as 24 hours. That apply-once model reduces repeated paperwork and produces multiple loan offers for comparison.
Core Features
An online application collects basic business and personal details and matches you to multiple lenders so you complete forms only once. Financing choices include SBA loans, equipment financing, lines of credit, and receivables funding, and Lendio pairs you with an advisor during offer review. The platform also emphasizes transparent communication and support through the approval process.
Key Differentiator
Lendio centers its value on a wide lender network and human advisor support, giving you many competitive offers from a single application. Compared with Lending Gurus, which uses an AI conversational advisor to match borrowers rapidly, Lendio focuses more on breadth of lender choice and traditional advisor guidance.
Pros
A large lender network gives you a broad set of offer types and terms so you can compare alternatives. The single-application flow saves time when you need working capital quickly, and advisor assistance helps interpret loan terms and fees. Many customers praise the platform for clear communication and faster fund delivery when available.
Cons
- Inconsistent follow-up from loan representatives can leave applicants waiting after the initial contact.
- Interest rates often depend on the chosen lender, and some offers carry high rates compared with bank loans.
- Some customers report hidden fees or loan terms that feel unfavorable once the offer arrives.
- Reaching the same agent after initial contact can be difficult, producing uneven approval experiences.
When It May Not Fit
- If you require bank-grade interest rates or jumbo specialized loans, Lendio is not the best match.
- If you operate outside the United States you may not be eligible for financing through the platform.
- If you need personalized in-branch banking relationships rather than marketplace matches, look elsewhere.
Who It’s For
You are a small to medium-sized business owner who values fast access to a variety of lenders and clear guidance during offer selection. You accept that loan pricing will vary across lenders and that you want the convenience of one application. This fits operators with moderate revenue who need working capital, equipment funding, or SBA support.
Real World Use Case
A retail owner applies online and uploads basic business and personal documents. Within days they receive multiple term sheets and review options with a Lendio advisor. The owner selects an offer that covers seasonal inventory, and funds arrive quickly so stock is available before peak sales.
Pricing
Submitting an application on Lendio is free. Loan costs, interest rates, and fees vary by lender and product. Funding amounts span a few thousand dollars up to several million dollars depending on the lender and loan type.
Website: https://lendio.com
Biz2Credit
At a Glance
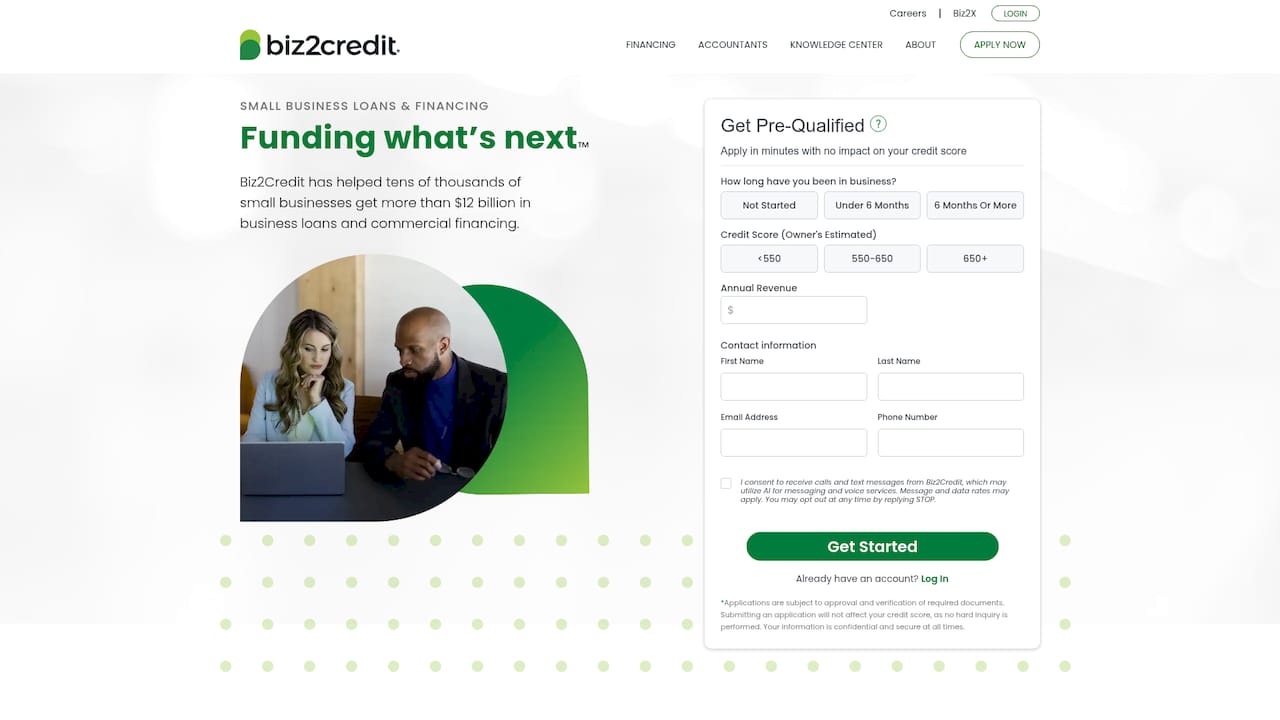
Biz2Credit’s marketing materials state decisions are often made within 24 hours. The platform acts as a lending marketplace that matches small businesses with multiple funders. It emphasizes an all digital application and offers a range of loan and credit products for U.S. businesses.
Core Features
Biz2Credit handles vendor onboarding and marketplace integration while offering a fast online application and prequalification step that reduces paperwork. The platform lists term loans, revenue based financing, and lines of credit, and it also includes secure document storage plus dedicated support from small business finance experts. Those elements combine to let an owner compare options from multiple lenders in one place.
Key Differentiator
Biz2Credit centers on direct access to several lenders through a digital marketplace, which helps owners see more options than a single lender can provide. That focus makes it better suited to owners who want marketplace choices rather than a guided AI match and concierge service. It targets businesses that prefer to review lender offers themselves.
Pros
The application process is quick and largely digital, which reduces time away from running the business. The platform lists many financing types, so you can pursue growth capital, working capital, or a line of credit without contacting multiple lenders. Customer support and expert guidance are available, and the site provides educational content and success stories for owners who want examples.
Cons
- Mixed user reviews call out unclear fee disclosures and reports of hidden costs.
- Document verification can be slow and feels cumbersome for owners with limited admin time.
- Customer support has reported long wait times and inconsistent communication.
- Some loan offers may include upfront costs that are not clearly detailed in initial quotes.
When It May Not Fit
If your business is based in a state where certain products are unavailable, this marketplace may not deliver the options you need. If you require immediate, hands on local banking relationships, the online marketplace model will feel remote. If you need fully transparent, line item fee disclosure before application, some users report the platform falls short.
Who it’s for
Small business owners and entrepreneurs across the United States who want quick, digital first access to multiple lender choices will find this useful. It fits owners who can assemble basic documents online and who prefer comparing lender offers themselves. It is less suitable for businesses that need in person banking or guaranteed fee schedules upfront.
Real World Use Case
According to the company, a small retail owner in California applied for a $50,000 term loan and received a quick decision and funding within a few days. The entire process ran online, with the owner uploading bank statements and managing repayments remotely. That scenario reflects how the marketplace shortens vendor shopping and execution.
Pricing
Loan sizes range from $25,000 to $2 million, and some products require a minimum credit score of 650 and annual revenue of $100,000 or more. Lines of credit are available up to $500,000 with pay as you draw terms. Specific fees and rates vary by lender and loan type, and some users report unclear fee disclosure.
Website: https://biz2credit.com
Approvd
At a Glance
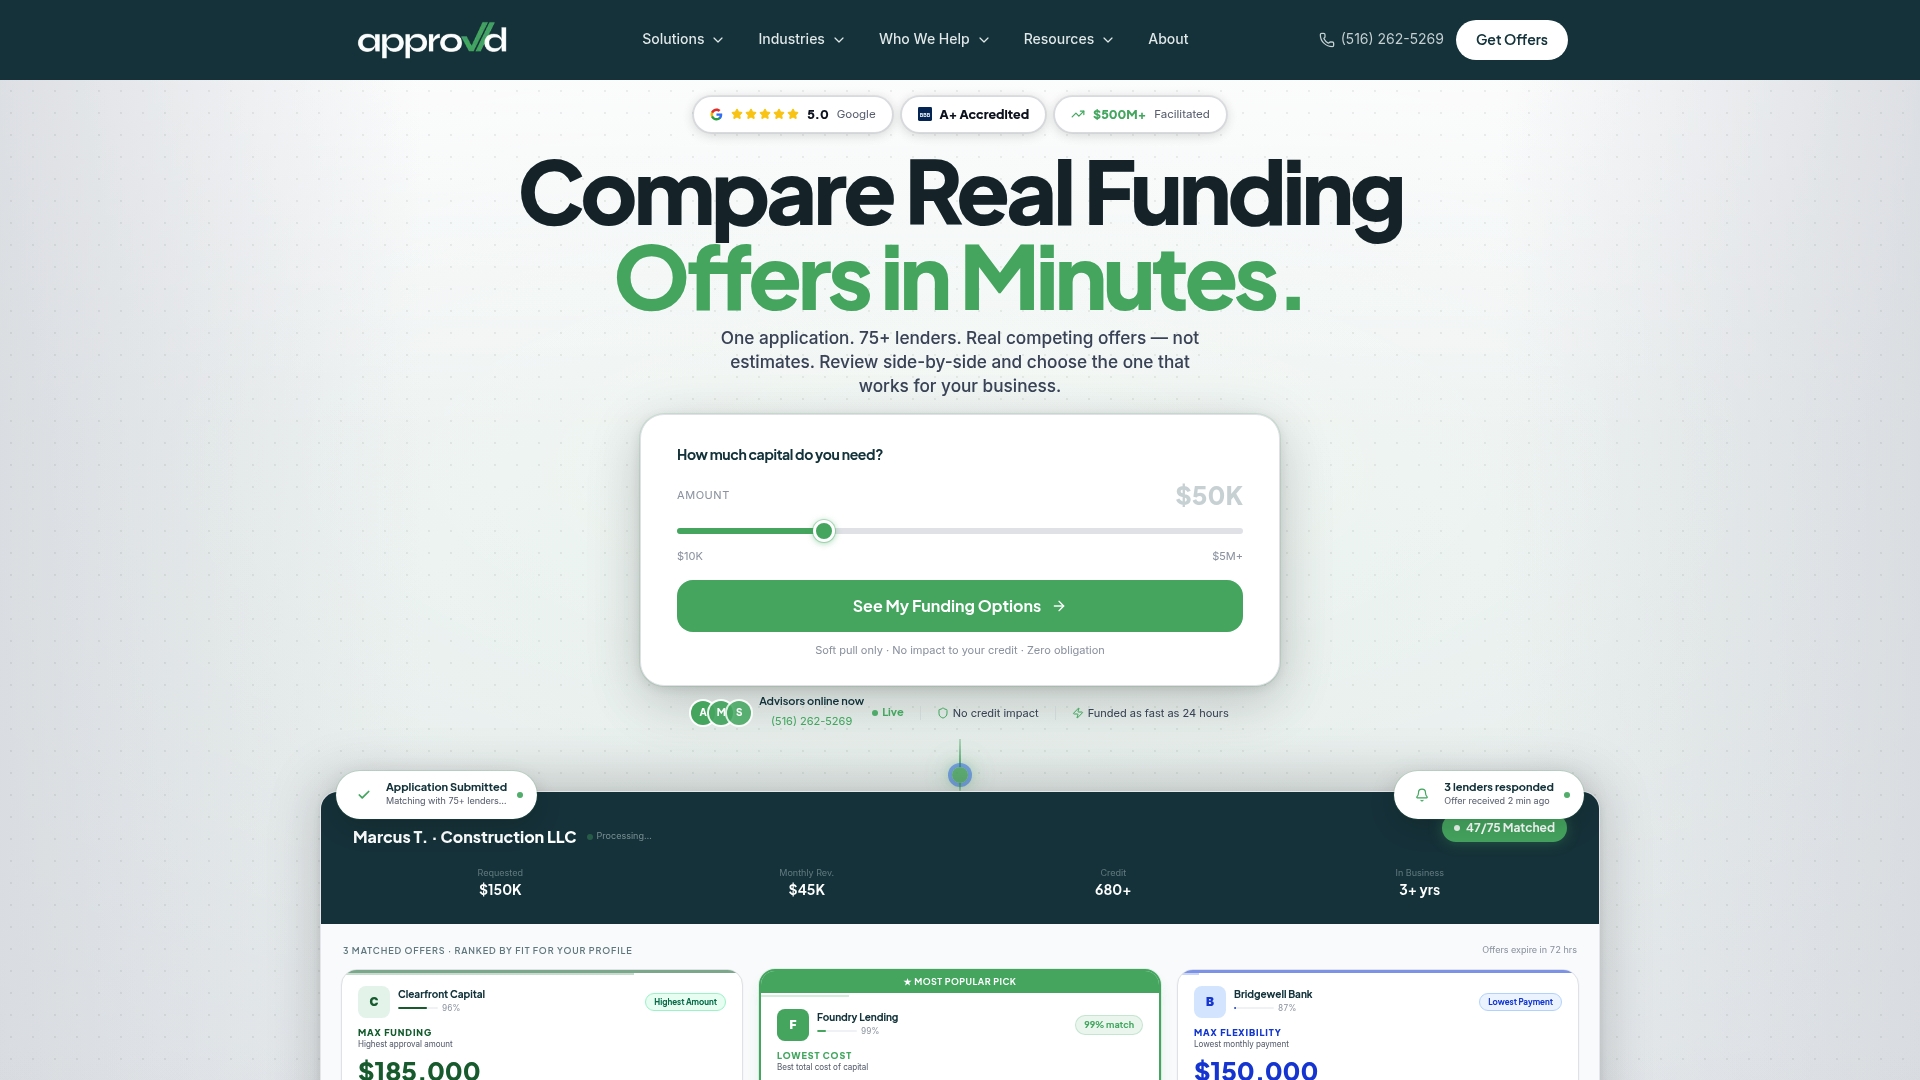
More than 75 lenders are accessible through a single application on Approvd. That breadth gives small business owners a practical way to compare loan proposals without filling many forms. The marketplace pairs automated matching with human advisors so you see multiple quotes side by side. This model shortens the search for capital while keeping paperwork minimal.
Core Features
The single application routes basic business details to a network of lenders and the platform returns competing proposals. A real-time matching engine ranks offers and presents them side by side, while dedicated advisors review terms and help interpret pricing. Approvd’s marketing materials state funding is often available within 24 hours, and the application does not impact your credit score during the search.
Key Differentiator
The standout is the blend of automated matching and personalized human advisory. That mix helps owners who need fast results and prefer expert guidance when comparing loan terms. The marketplace also advertises no impact on credit scores while you shop, which reduces the risk of multiple hard inquiries.
Pros
The platform gives access to a wide lender network, which increases the chance of finding a product that fits your cash flow profile. The combination of quick matching and advisor support reduces back-and-forth and speeds decision making for time sensitive needs. Transparent, side by side offer presentation makes fee and repayment comparisons straightforward for owners who lack dedicated finance teams.
Cons
- Limited third-party reviews exist online, so independent references can be hard to find.
- The marketplace focuses on small and medium-sized businesses and may not suit very large enterprise financing needs.
- The service description does not list loyalty rewards or exclusive discounts for repeat customers.
When It May Not Fit
If you run a large company that requires multi tranche financings or bespoke syndications, this marketplace is likely too narrow. If independent, peer-verified reviews matter to you, the sparse third-party coverage is a drawback. Businesses that want negotiated ongoing discounts or loyalty benefits will find limited evidence of those perks.
Who It’s For
Small to medium-sized business owners who need quick access to working capital, equipment loans, or debt consolidation will find this model helpful. Owners who prefer to compare offers themselves but want an advisor to check terms will benefit most. This is also a fit for companies that want to avoid multiple hard credit pulls while shopping.
Real World Use Case
A retail owner with seasonal inventory needs submits basic revenue and business details through the single application. Approvd returns multiple lender proposals and an advisor highlights the true cost differences. The owner picks the clearest offer and completes documents, then receives funds in time for the selling season according to the vendor timeline.
Pricing
Exploring funding options on Approvd is free with no application fee. Actual interest rates, origination fees, and repayment schedules vary by lender and loan product. Final costs depend on the offer you accept and the lender’s underwriting.
Website: https://yourapprovd.com
Validus
At a Glance
Operations span Indonesia, Thailand, Vietnam, and Singapore, serving small and medium enterprises across Southeast Asia. Established in 2015, the marketplace links corporate partners and public programs to lenders for working capital. The platform prioritizes collateral-free options and faster fund access for SMEs.
Core Features
The marketplace supports vendor onboarding for corporate partners and offers multiple financing tracks, including invoice financing and purchase order financing, plus working capital loans. It works with major corporations and government-backed schemes to broaden access and accelerate approvals. Multi-country operations let vendors and buyers use the same platform across several Southeast Asian markets.
Key Differentiator
Validus pairs regional corporate partnerships and government collaborations with multiple financing choices to expand access for SMEs. That mix gives supply chain participants an on-ramp to funding tied to commercial relationships. The result is a model focused on inclusion and speed rather than traditional collateral requirements.
Pros
Strong presence across Southeast Asian markets supports local knowledge and regional deal flow, which matters when lenders evaluate invoices tied to local buyers. Partnerships with corporations and government schemes add credibility and can unlock vendor pools that standalone platforms cannot reach. A variety of financing options helps businesses pick between invoice factoring, PO finance, and short-term working capital based on immediate cash needs.
Cons
-
Limited public transparency about fees and interest rates makes early comparisons harder for cash flow planning.
-
Public reports mention withdrawal issues and slow support responses, which could affect reliability during urgent funding needs.
-
Few independent third-party reviews exist, so user experience appears mixed across markets.
-
Product documentation lacks consistent detail on eligibility rules across countries.
When It May Not Fit
If your business operates outside Southeast Asia, this marketplace will probably not meet your needs. Larger multinational corporates seeking cross-border facilities beyond these markets may find the product scope narrow. Firms that need fully transparent, prepublished fee schedules may prefer lenders with published rate sheets.
Who It’s For
SMEs across Southeast Asia that need quick access to cash against invoices or purchase orders will find this platform relevant. Vendors working with large corporate buyers who can use vendor onboarding will gain the most benefit. Smaller exporters or startups without bank collateral seeking alternative working capital solutions also fit the profile.
Real World Use Case
A mid-sized Indonesian manufacturer used invoice financing on the platform to unlock funds tied to several unpaid invoices. The company completed onboarding with its corporate buyer and received funds within days. They deployed the cash to buy inventory and fulfill a larger incoming order.
Pricing
Pricing varies by product and market and is disclosed during application. Typical offerings include collateral-free loans and invoice factoring with interest rates and fees provided case by case. Transparent rate examples are not published publicly.
Website: https://validusgrp.com
Investree.id
At a Glance
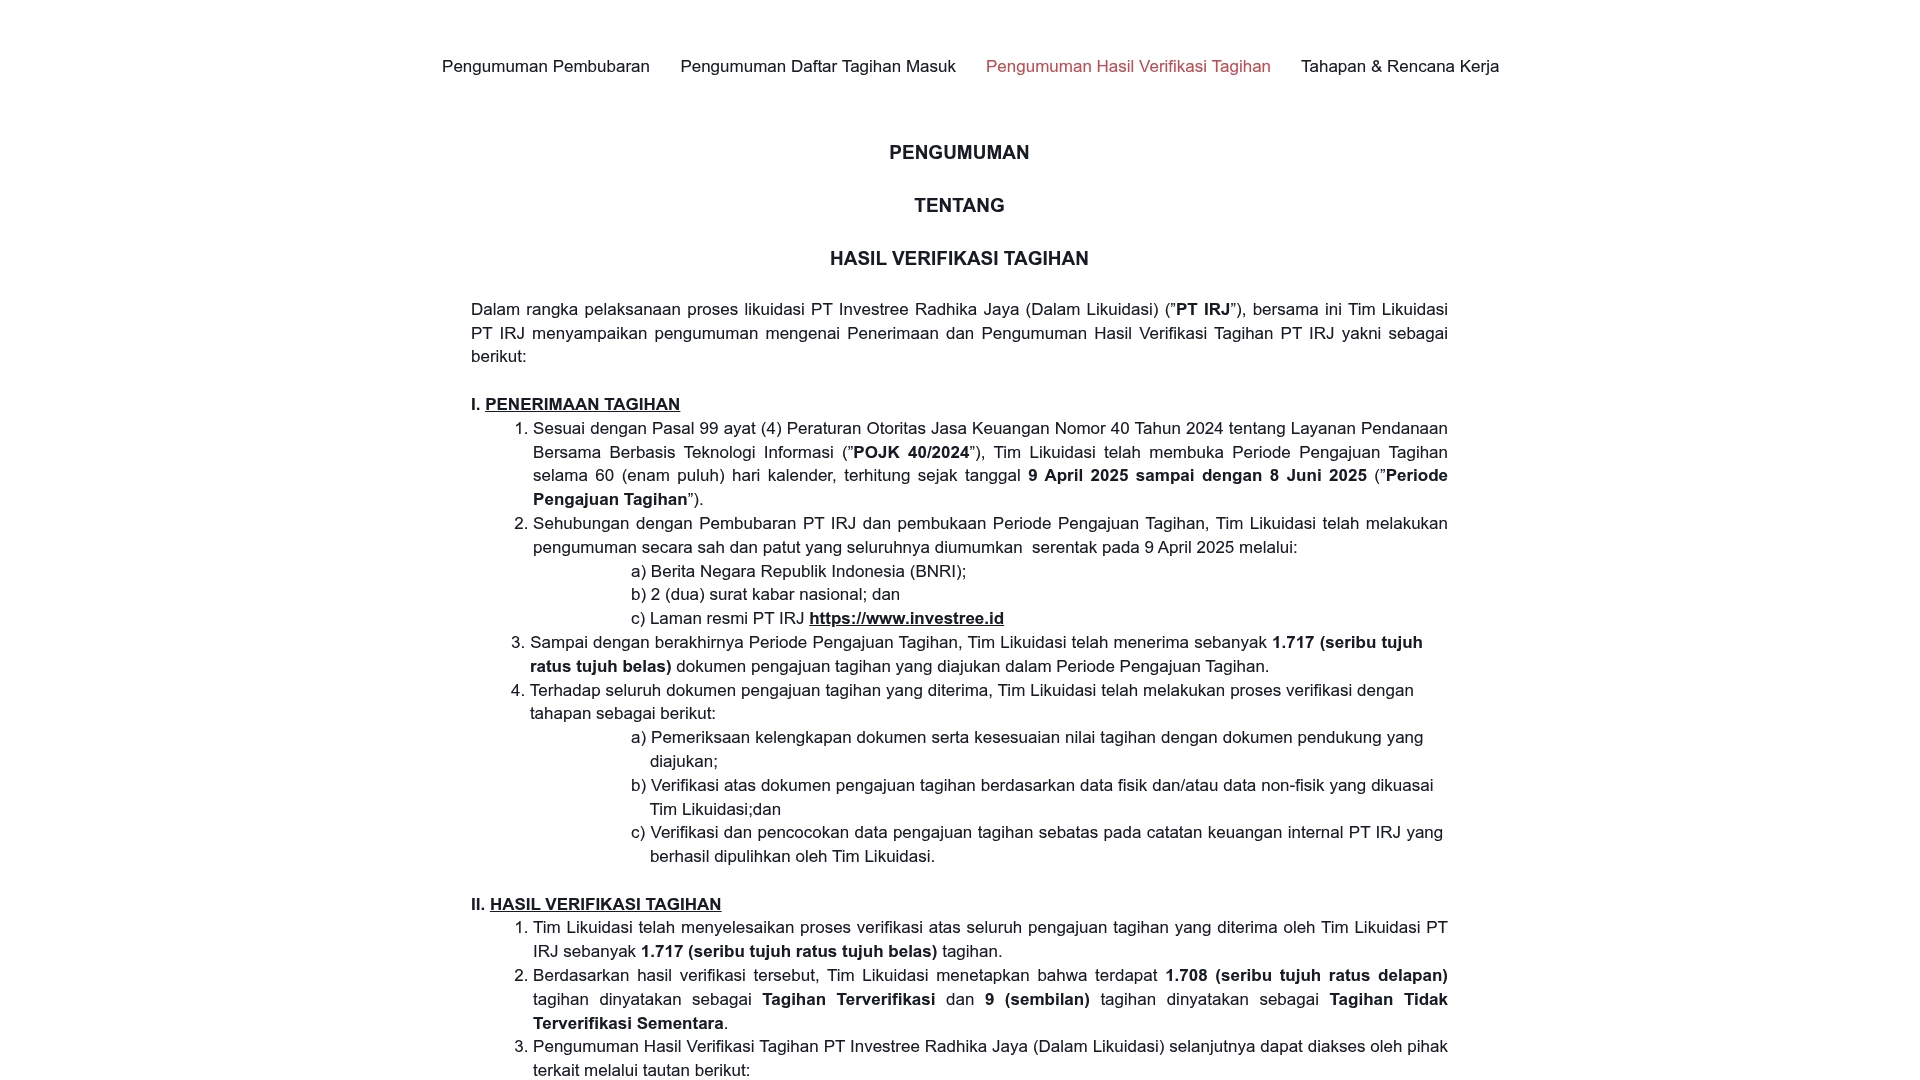
Investree.id’s marketing materials state it operates under POJK 40/2024, a specific Indonesian regulator framework for financial claim marketplaces. The site focuses on submitting and verifying receivable claims during legal and liquidation processes. The platform emphasizes transparent reporting and official communication between claimants and investors.
Core Features
Investree.id centralizes claim submission and verification with tools for tracking progress and attaching documentation. The platform publishes verification results and maintains official channels for updates, which helps legal teams and investors follow each case. Those combined features aim to reduce dispute friction and speed decision making for receivables funding.
Key Differentiator
The platform’s main distinction is its positioning as a regulation-oriented marketplace that concentrates on documented claim verification inside Indonesia. That regulation focus shapes workflows, reporting, and the communication model between businesses, legal entities, and funders.
Pros
Because the site aligns its processes to local rules, it offers a clear, traceable path for submitting claims and documenting outcomes. The platform supports official communication, which reduces uncertainty when multiple parties review claims. Transparency in verification results helps investors decide which receivables to fund and gives businesses a documented record for auditors or liquidators.
Cons
- Limited user-experience details: public information does not describe the interface or how easy the submission flow feels.
- Sparse independent feedback: there is no visible third-party review data to confirm real user experience or satisfaction.
- Geography bound: the service focuses on Indonesia and may not accept cross-border claim processing.
- Narrow scope: the site concentrates on claim verification and does not handle general payment processing or broad lending products.
When It May Not Fit
If you need a global receivables platform, this service will likely be too limited because it restricts operations to Indonesia. If your priorities include integrated payment collection or varied lending products, this site will not meet those needs. The limited public detail on the user interface also makes it hard to recommend for teams that need an intuitive self-serve workflow.
Who It’s For
Financial institutions, legal professionals, and investors reviewing receivables in Indonesia will find the platform relevant. Mid-sized businesses and liquidation trustees that require documented claim verification will benefit from its reporting and official communications. Small exporters or nonresident companies will likely find the geographic focus misaligned with their needs.
Real World Use Case
A mid-sized Indonesian company files claims for unpaid invoices during a receivership. The business uploads documentation, follows verification steps, and receives status updates through the platform’s official channels. Investors then inspect verified claims and fund selected receivables with a clear audit trail.
Pricing
No public pricing is listed. The platform describes itself as a regulatory and claim management site rather than a storefront, so firms must contact the operator for engagement terms and any fee schedule.
Website: https://investree.id
Comparison of alternatives
For small business owners prioritizing financing efficiency and credit protection, Lending Gurus stands out for its AI-driven personalized matching without hard credit inquiries. Competitors also offer compelling benefits tailored to other needs, from broad lender diversity to transparent fee comparisons, resulting in distinct advantages depending on your scenario.
Matching Workflow Efficiency
Lending Gurus distinguishes itself by eliminating hard credit inquiries during lender matching, allowing users to explore funding options risk-free. In contrast, Lendio and Biz2Credit involve traditional applications requiring document uploads but extend a wider lender network. Validus, while unique due to regional partnerships, caters solely to Southeast Asian markets and thus excludes U.S.-based business operators.
Offer Presentation and Fee Transparency
Approvd excels in providing side-by-side comparisons of loan offers, simplifying decision-making and enabling business owners to quickly identify the most favorable terms. Biz2Credit, although similar as a lending marketplace, has noted instances of unclear fee disclosures among users, which may pose challenges for businesses emphasizing upfront clarity in financial commitments. Lending Gurus promotes its commitment to transparent compensation disclosures, ensuring users are aware of funding terms.
Best fit
- If you prioritize protecting your credit during the financing search, Lending Gurus provides access to diverse loans without credit scoring impact.
- For advisor-supported proposal comparisons, Approvd’s transparent, ranked presentations shine.
- If access to an expansive lender network is your focus, Lendio connects users with a broad pool of vetted partners.
- Owners emphasizing detailed fee transparency should consider the clear presentation style visible in Approvd’s matched proposals.
Our pick
With Guru, Lending Gurus excels for users seeking intuitive financing workflows that avoid risking their credit standing during searches. While other platforms offer helpful lender networks and comparison tools, Lending Gurus’ conversational AI approach delivers immediate, risk-free personalization for scenarios where rapid tailored options matter the most.
Leveraging conversational AI, this comparison highlights platforms for tailored, accessible business financing solutions.
| Platform | Key Differentiator | Best For | Pricing | Notable Limitation |
|---|---|---|---|---|
| Lending Gurus | AI-driven conversational advisor for lender matching | U.S.-based owners needing quick, no-credit-hit options | Free for users | Dependent on lender partner availability and terms |
| Lendio | Wide lender network with advisor guidance | Small businesses seeking diverse loan offers | Free application | Inconsistent follow-up and reported hidden fees |
| Biz2Credit | Quick digital marketplace for multiple offers | Owners preferring an all-digital application process | Minimum draws at $25,000 | Mixed reviews on support response |
| Approvd | Advisor-assisted matches with transparent offers | Businesses wanting clear side-by-side comparisons | Free application | Limited third-party reviews and enterprise solutions |
| Validus | Regional access for Southeast Asia SMEs | SMEs in Southeast Asia requiring invoice financing | Pricing case by case | Limited fee transparency and geographic coverage |
How to Find Reliable Invoice Financing That Matches Your Business Needs
Invoice financing can feel complex when you need fast access to cash but want to avoid damaging your credit score. Many best invoice financing companies require detailed paperwork and hard credit pulls that slow down your funding and may impact your rating. Lending Gurus solves this problem by using a conversational AI advisor named Guru. It listens to your situation and finds lender matches in minutes without a hard credit inquiry or long forms.
With Lending Gurus, you benefit from tailored loan options across multiple finance categories, including invoice funding, all delivered quickly and without obligation. Explore how Lending Gurus helps U.S.-based small business owners and entrepreneurs compare and choose financing solutions that fit their unique cash flow needs.
Looking for straightforward invoice financing options with no credit score impact?
Visit Lending Gurus to connect with lenders matched to your business in just minutes and find financing without the typical delays or hurdles.
FAQ
How does Lending Gurus’s matching process work for invoice financing?
Lending Gurus uses an AI conversational advisor named Guru to create a borrower profile through a chat interface. This feature allows users to describe their financial situations in plain language, significantly streamlining the process compared to traditional applications. Take advantage of this streamlined approach to find suitable lenders without the usual paperwork burden.
What is the difference between Lending Gurus and Lendio for invoice financing?
Lendio benefits users by providing access to a marketplace of 75 vetted lenders and offers advisor support during the offer review process. In contrast, Lending Gurus specializes in a more personalized experience through its AI-driven conversational match, making it a better fit for those who prefer quick, AI-assisted guidance without a hard credit inquiry. Both platforms cater to different user needs depending on whether they prioritize personal assistance or automated matching.
What types of loans can I compare using Lending Gurus?
Lending Gurus allows users to compare a variety of loan types, including business loans, personal loans, equipment financing, invoice funding, and real estate financing. This diversity enables small business owners to explore multiple financing options tailored to their specific needs. Users can confidently review various lending solutions based on their financial circumstances.
Can I use Lending Gurus if I want to avoid a credit inquiry while assessing my options?
Absolutely, Lending Gurus does not require a hard credit pull to begin searching for loan options. This feature allows users to shop for financing without impacting their credit scores, making it an ideal starting point for those concerned about credit inquiries affecting their standings.
Does Lending Gurus charge any fees to users for accessing financing options?
Lending Gurus is free to users, and it earns compensation from lenders when matches lead to funded deals. This model allows business owners to browse financing options without incurring costs, making it an accessible choice for small business financing needs.
