
Finding working capital for your online store without hitting slow approvals or risky terms feels unpredictable and complicated. Many direct lender programs restrict eligibility with high sales minimums, hidden fees, or rigid repayment schedules that ignore cash flow swings. This guide covers pricing, lender network size, and repayment structures across six business lending marketplaces so you can pick a funding match for your store’s growth.
Table of Contents
Lending Gurus
At a Glance
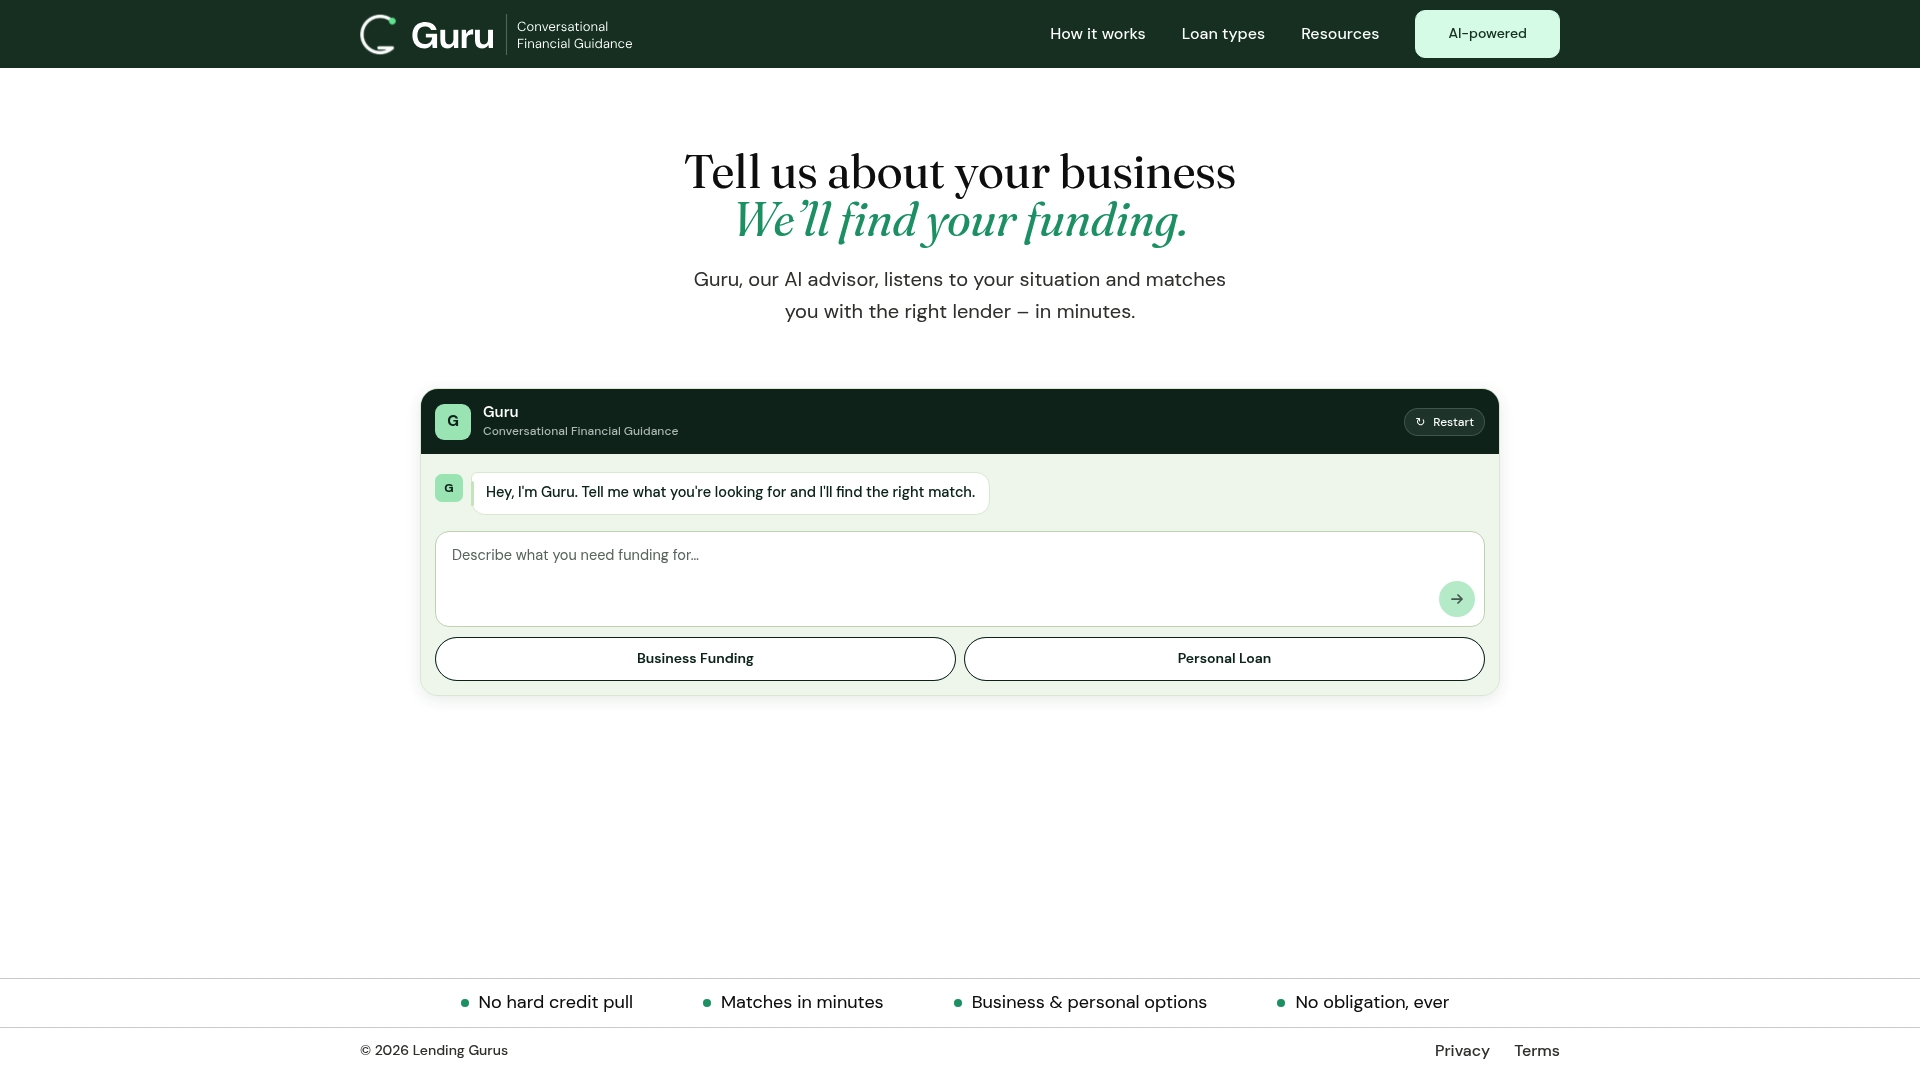
The vendor advertises matching in minutes via a conversational AI advisor named Guru, which asks targeted questions and avoids a hard credit pull. That approach lets you explore options without an immediate hit to your credit record. The platform focuses on both business and personal funding, from working capital to auto and student loan refinancing.
Core Features
Lending Gurus uses a conversational intake that replaces long application forms and gathers context through chat-style prompts. The system connects applicants to third-party lenders across business and personal loan categories, including equipment, real estate, and debt consolidation. The service operates at no cost to applicants because the platform receives fees from lender referrals.
Key Differentiator
The defining capability is the conversational interface that recommends tailored lender matches without requiring initial forms or a hard credit pull. That method keeps the discovery phase light and lets you compare options before a formal application. The model relies on lead generation to surface compatible lenders rather than presenting fixed in-house loan products.
Pros
The conversational flow reduces time spent on paperwork while still collecting enough detail to surface relevant lenders. Because the platform avoids a hard credit inquiry during matching, your credit score remains unaffected during the exploration stage. The marketplace covers business and personal needs and is transparent about earning commissions from lender partners.
Cons
- Depends on third-party lenders, so final loan terms vary and are not guaranteed
Who It’s For
Entrepreneurs and individuals in the U.S. who want a quick, chat-based way to find lenders fit for a specific need will find this useful. You should prefer discovery without immediate credit impacts and value getting matched rather than shopping lender-by-lender. If you need guaranteed rates or control over which lenders bid, this model may not fit.
Unique Value Proposition
Matching without a hard credit pull during discovery lets you compare options without risking your credit score. That workflow reduces the cost of shopping multiple lenders and lowers the friction of early-stage price discovery. For business owners worried about repeated credit inquiries, this preserves the ability to test several alternatives before committing.
Real World Use Case
A small retailer short on seasonal cash talks with Guru about a $10,000 working capital need and receives a shortlist of lender matches through the chat flow. The owner reviews suggested programs, then pursues a formal application with the preferred lender. The process removed manual form-filling and avoided a hard credit check until the owner chose a provider.
Pricing
There is no charge to applicants. The platform earns commissions from lenders after successful funding, which means you can use the service free while lenders compensate the marketplace. Final borrower costs depend entirely on the lender you select and their disclosed rates and fees.
Website: https://lendinggurus.com
Lendio
At a Glance
Lendio reports a network of more than 75 verified lenders available through its marketplace. According to the company, many applicants see approval and funding within 24 hours when their applications match lender criteria. That lender breadth and speed aim to shorten the time you spend shopping for the right small business loan.
Core Features
The marketplace matches your application against a large lender network and presents multiple loan types such as SBA loans, equipment financing, lines of credit, and accounts receivable financing. The platform supports AI-driven loan matching and digital applications, and it offers business calculators and resource guides to help you compare offers. Lendio also provides embedded financing solutions so third-party platforms can present financing without building their own loan system.
Key Differentiator
Lendio pairs a wide lender network with embedded financing capabilities and automated matching. That combination lets you compare distinctly different offers from one interface and lets platforms bring financing directly into their checkout or onboarding flows. The focus is on choice and integration rather than a single proprietary loan product.
Pros
Lendio connects many verified lenders, which increases the chance that one will fit your credit profile and funding need. The online application reduces paperwork and centralizes multiple offers so you can compare terms in one place. The company advertises fast funding and reports strong customer satisfaction, and those elements make the marketplace useful when you need capital quickly and want options.
Cons
- Inconsistent communication: some customers report difficulty getting clear updates during underwriting.
- Cost variability: loan interest rates and fees depend on the chosen lender, and offers can include complex terms.
- Sales pressure: several users mention aggressive follow-up from lenders or brokers.
- Transparency gaps: last-minute changes to terms and limited clarity on refinancing options are reported.
When It May Not Fit
If your business is outside the United States, you will likely find few or no suitable lenders on this marketplace. Businesses with thin or poor credit profiles may receive offers with high interest rates or limited options. If you need fully transparent refinancing paths, the marketplace can be uneven because refinancing availability and disclosures differ by lender. If you prefer a single direct lender relationship, the comparison model adds extra coordination.
Who It’s For
This marketplace suits small business owners who value choice and fast comparisons across loan types. It fits entrepreneurs buying equipment, filling seasonal inventory, or seeking lines of credit without long bank waits. It also fits platform owners who want embedded financing options for their customers.
Real World Use Case
A retail owner compares term loans and equipment financing in a single session and selects the cheapest, fastest offer. The owner completes the digital application, uploads basic documents, and accepts an offer that funds within a short window. The platform tools then help track payment dates and lender communications.
Pricing
Application submission through Lendio is free. Actual loan pricing, interest rates, and fees are set by individual lenders. The company notes some loans may include origination fees typically around 5% depending on the lender and product.
Website: https://lendio.com
Approvd
At a Glance
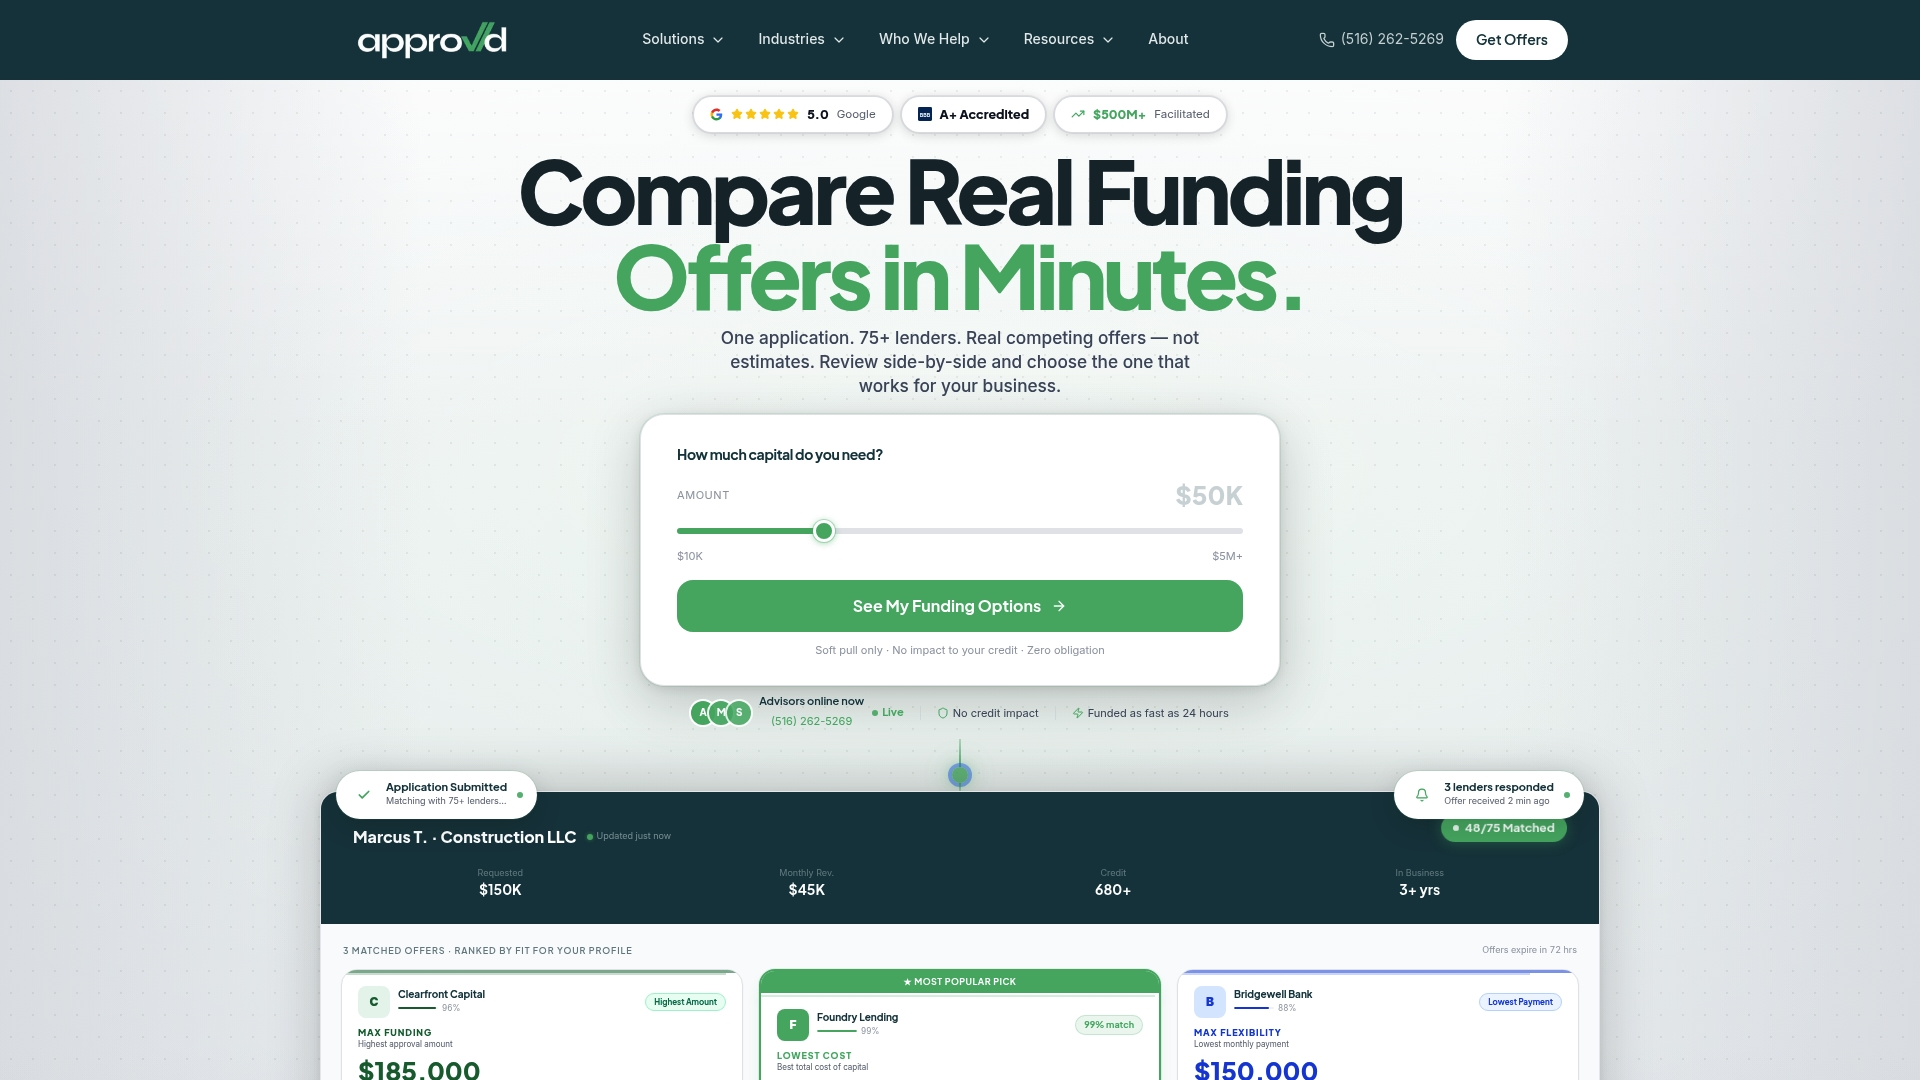
Approvd connects small businesses to a network of 75+ lenders through a single application. The platform uses soft pulls for prequalification so your credit score is not impacted. According to the company, funds are often available within 24 hours after you accept an offer.
Core Features
Approvd matches applicants to many funding products, including revenue based financing, lines of credit, term loans, SBA loans, equipment financing, and debt consolidation. The service pairs automated matching technology with dedicated advisors who review offers and answer questions. Approvd delivers real, competing offers with transparent rates and terms so you can compare options side by side.
Key Differentiator
Approvd blends automated matching with human advice to surface multiple lender offers quickly. That mix helps you weigh trade offs across interest cost, repayment cadence, and lender terms. The marketplace model focuses on choice rather than single lender placement.
Pros
Approvd gives access to a deep lender pool, which increases the chance of finding product terms that fit your cash flow needs. The use of soft pulls for prequalification protects your credit score while you shop offers. Advisors guide negotiations and paperwork, and the platform advertises rapid funding once you accept an offer, which can speed project timelines.
Cons
- Limited independent review data. Third party reports raise cautious concerns about some lender practices.
- Marketing claims have led to reports of misleading or predatory offers from certain lenders.
- Not a direct lender. You will not get traditional bank relationship benefits from Approvd.
- May not serve businesses located outside the United States.
When It May Not Fit
If you need a direct banking relationship or bank issued loans, this marketplace will not provide them. If you operate primarily outside the United States, Approvd may not have lender coverage. If you require independently audited lender behavior, the limited third party review data could be a problem.
Who It’s For
Business owners with at least six months of operations who want multiple funding options fast will benefit most. Owners with variable credit profiles who prefer advisor support to interpret offers will find the model helpful. Retailers, service providers, and light manufacturing firms needing inventory or equipment financing are typical fits.
Real World Use Case
A retail owner applies once and receives competing offers from different lenders. An advisor reviews rates and repayment schedules and highlights which offer suits seasonal inventory needs. The owner accepts one offer and receives funds within days without a hard credit hit.
Pricing
Applying through Approvd is free. Loan amounts, rates, and fees vary by the issuing lender and chosen product. There is no single price range because Approvd connects you to multiple third party lenders.
Website: https://yourapprovd.com
Clearco
At a Glance
Clearco’s marketing materials state it has invested over $3 billion across more than 10,000 brands. The vendor advertises approvals in as little as 24 hours and uses AI underwriting to speed decisions. That scale claim and the rapid approval pitch position Clearco as a fast option for growth capital aimed at scaling brands.
Core Features
Clearco delivers flexible funding through revenue based financing and options labeled as fixed and rolling capacity, which adapt to seasonal needs. The platform links to sales and payment channels to verify revenue, and it uses AI underwriting to support faster decisions. No collateral or personal guarantees are required per the product information.
Key Differentiator
Clearco focuses on growth capital that does not take equity and that adjusts to sales performance. That focus, paired with its emphasis on speed, separates it from lenders that require fixed monthly payments or equity stakes. The company frames itself as a partner for scaling merchants and software companies.
Pros
Clearco offers access to capital without giving up equity, so founders keep ownership while funding growth. The lack of collateral and personal guarantees reduces founder risk compared with secured loans. The onboarding experience and dashboard are straightforward, and some customers get hands on support from account managers during funding and reconciliation.
Cons
-
Stricter cash on hand requirements could exclude businesses with irregular cash flow.
-
Users report inconsistent account management experiences across different accounts.
-
Costs can be higher than some alternative funding sources, depending on growth and risk profile.
-
Underwriting rules have shifted over time, which can create friction during account transitions.
When It May Not Fit
Clearco requires a stable revenue stream and specific thresholds, including at least $100,000 per month and 12 months of consistent revenue. The product supports only U.S. based businesses with active U.S. bank accounts. If your business is pre revenue, early stage, or non U.S. based, Clearco will likely be the wrong fit.
Notable Integrations
Clearco connects directly to Shopify, Amazon, Stripe, PayPal, BigCommerce, and Square to verify sales and cash flow. Those links speed the application review and ongoing reconciliation for merchants that sell across platforms.
Who It’s For
Ecommerce and SaaS founders in the U.S. who already generate steady monthly revenue and who want growth capital without giving up equity will find Clearco relevant. Operators seeking funding for inventory, marketing, or channel expansion fit the profile. Businesses that cannot meet the revenue thresholds should look elsewhere.
Real World Use Case
A fashion brand uses Clearco to buy inventory ahead of seasonal launches and to fund a paid marketing push. Clearco verifies recent sales via Shopify and Stripe and releases capital to cover production and ads. The brand keeps ownership and repays as sales come in, which smooths cash flow through the season.
Pricing
Clearco charges fixed, performance based rates that vary by growth and risk profile. Specific pricing depends on your revenue history and the funding structure you choose. The company does not publish a single rate table for all applicants.
Website: https://clear.co
Wayflyer
At a Glance
Wayflyer reports deploying more than $6 billion in business capital and claims it has funded 7,000+ brands. The vendor advertises funding offers tailored from real-time performance data. That positioning targets merchants who need large, rapid access to growth capital without equity or personal guarantees.
Core Features
According to the company, applications can be completed in about 12 minutes and funds deposited in as little as 24 hours. The platform uses real-time sales and performance data to produce tailored merchant cash advance offers and repayment schedules. Wayflyer also supports high maximum advances up to $20 million and structures repayments to align with business cash flow cycles.
Key Differentiator
Wayflyer emphasizes instant underwriting driven by business performance signals instead of traditional credit measures. That approach lets offers reflect seasonal sales variability and inventory needs. The result targets merchants who can demonstrate predictable online revenue streams.
Pros
The application and decision flow is automated, which speeds approvals for merchants who have connected sales and advertising data. Customer service receives positive mentions for responsiveness and clarity, and the platform keeps contractual terms transparent without hidden fees. Funding can be used flexibly for inventory, marketing, or operational needs, and the company notes institutional investor backing that supports larger advance sizes.
Cons
- Some merchants report the underwriting process can feel slow or opaque. This inconsistency affects the user experience for a minority of applicants.
- Support communication has occasional gaps, resulting in differing account manager responsiveness for multi-store merchants.
- Contract terms may read as aggressive for companies seeking long-term, low-cost debt instead of merchant cash advance structures.
- Interpreting complex, multi-store data can be difficult for merchants without analytics resources.
When It May Not Fit
Very early stage businesses with little or no revenue will not produce the performance data this model requires. Companies seeking traditional long-term term loans with fixed amortization may find the merchant cash advance approach misaligned with their capital needs.
Who It’s For
Ambitious e-commerce and retail brands that generate predictable online revenue and want growth capital without giving up equity or providing personal guarantees. Typical users range from direct-to-consumer brands preparing inventory buys to wholesalers timing seasonal campaigns. Merchants with connected sales and ad platforms will get the fastest decisions.
Real World Use Case
A small online apparel retailer used Wayflyer to secure $150,000 in under 24 hours, enabling an inventory buy ahead of a holiday window. That speed let the merchant increase stock levels without tapping personal assets. The capital funded marketing and supply chain timing until sales caught up.
Pricing
Pricing is not listed publicly for a fixed product tier. Wayflyer operates on merchant cash advance terms that vary by offer and business profile, and advance costs depend on the tailored agreement presented during underwriting.
Website: https://wayflyer.com
Onramp Funds
At a Glance
The vendor advertises funding within 24 hours after you connect your store and bank accounts. Onramp Funds ties repayment to a percentage of daily sales, which shifts payments with your revenue. The offering targets US eCommerce sellers with at least six months of history and monthly sales above $10,000.
Core Features
Onramp Funds issues multiple funding types, including fixed, variable, and revolving cash lines, so you can pick an offer that matches seasonality or a short campaign. The platform prequalifies quickly and claims fast funding, then pulls sales and order data via direct storefront connections to enable automatic data collection. Fees are presented as flat charges or sales percentages rather than fixed monthly payments.
Key Differentiator
The primary distinction is the direct storefront integration that makes offers performance based. That connection lets Onramp Funds size and schedule repayments around real sales instead of a fixed loan amortization. This design favors merchants whose cash flow rises and falls with promotions or inventory cycles.
Pros
Onramp Funds supports online sellers with funding products that align payment size to daily revenue so cash flow does not choke on a fixed monthly bill. The application and prequalification are fast, and the vendor claims funds can land within a day after setup. Multiple product types let you choose a short-term advance, a variable arrangement tied to sales, or a revolving cash line for ongoing needs. Store integrations reduce manual reporting and keep eligibility and repayment tied to actual performance. Capital comes without equity dilution, so you retain full ownership while accessing working capital.
Cons
-
High costs reported by users, with fees and effective interest that can add up over time.
-
Some sellers report unclear eligibility messages or inconsistent information from sales agents.
-
Post approval communication has been uneven for a number of merchants, making follow up difficult.
-
Several users describe trouble securing follow-on funding or disputes over collections and fees.
When It May Not Fit
This solution supports only US based sellers, so international merchants cannot apply. New stores with under six months of sales or monthly revenue below $10,000 will not meet the stated criteria. If your business is not an eCommerce storefront or marketplace seller, this product will not match your needs.
Notable Integrations
Onramp Funds connects directly to major storefronts and marketplaces. Integrations include Amazon, Shopify, Walmart, BigCommerce, WooCommerce, Squarespace, and TikTok Shop.
Who It’s For
You are a US eCommerce seller with at least six months of sales and monthly revenue north of $10,000. You need quick access to capital for inventory, marketing, or seasonal stocking without giving up equity. You accept performance based repayment tied to daily sales rather than a fixed monthly payment.
Real World Use Case
A Shopify fashion brand takes a fixed term cash advance to launch a new product line and pays a set share of daily sales until the advance clears. The brand uses proceeds to buy inventory and fund advertising before a seasonal spike. That timeline kept the marketing calendar funded without a fixed monthly loan payment.
Pricing
Pricing varies by product and by merchant. Offers typically use a flat fee or a percentage of sales to calculate total cost, and exact rates are set per deal. Specific rates are not listed publicly and are provided with each offer.
Website: https://onrampfunds.com
Comparison of alternatives
Business lending marketplaces each provide unique strengths to meet varied funding needs. Lending Gurus particularly distinguishes itself through its conversational AI interface, which offers personalized lender matching without a hard credit inquiry.
Lender Network Breadth
A notable comparison lies in the number of lenders each platform connects with. Lendio and Approvd both support networks exceeding 75 lenders, greatly widening the scope for applicants to access multiple financial products and competitive rates. However, this comes at the cost of deeper user interaction compared to Lending Gurus, which streamlines preference gathering via its conversational features.
Speed and Convenience
While Lending Gurus reduces application complexity through an interactive AI chat, platforms such as Wayflyer emphasize rapid access to significant funding amounts, particularly for businesses with connected performance data. Onramp Funds stands out with its automatic repayment integration based on daily store revenue, fitting ecommerce sellers with fluctuating cash flows. Conversely, Lending Gurus hosts a broader array of funding categories, balancing recommendation speed with diversification in lender options.
Best fit
- Entrepreneurs needing swift, customized lender matching without impacting credit scores benefit most from Lending Gurus.
- Businesses requiring access to an extensive lender network covering specific loan types should consider Approvd or Lendio.
- Companies tied to ecommerce sales and requiring revenue-based repayment flexibility will see the greatest utility in platforms like Onramp Funds or Wayflyer.
Our pick
Lending Gurus excels in presenting tailored lending recommendations via conversational AI while safeguarding applicants’ credit scores. Its approach uniquely avoids traditional form-based applications and credit inquiries during exploration. However, for businesses valuing deeper lender network breadth or integrations with ecommerce sales data, alternatives like Lendio or Wayflyer may align better with their needs.
Here’s a comparison to evaluate various platforms based on their standout features and capabilities:
| Provider | Key Feature | Best For | Pricing | Limitation |
|---|---|---|---|---|
| Lending Gurus | Chat-based matching without credit impact | Entrepreneurs needing diverse loans | No costs to applicants | Loan terms dependent on third-party lenders |
| Lendio | Large lender network with AI-driven matching | Fast small business loan comparisons | Price not published | Potential for aggressive lender follow-ups |
| Approvd | Advisor-guided automated lender matching | Businesses needing tailored support | Price not published | Mixed feedback on lender practices |
| Clearco | Revenue-based financing for growth brands | E-commerce businesses with revenue | Price not published | High revenue thresholds for eligibility |
| Wayflyer | Real-time performance-based offers | Merchants needing fast, large funding | Price not published | Not suited for early-stage or non-revenue businesses |
| Onramp Funds | Performance-based repayment options | Established U.S. eCommerce sellers | Price not published | Limited to U.S.-based online storefronts only |
What Options Do You Have Beyond Shopify Capital?
Small business owners often struggle with slow, invasive loan processes that impact credit scores and add complexity. Lending Gurus offers a solution by using an AI-powered conversational advisor called Guru. This platform matches you with lenders in minutes without hard credit checks, so your credit remains intact while you review personalized funding options for both business and personal needs.
Here is what you gain:
- Fast lender matching tailored to your situation
- No upfront credit score impact during discovery
- Clear guidance without filling lengthy forms
If you want a swift, transparent way to compare Shopify Capital alternatives, visit Lending Gurus to start a credit-friendly conversation with Guru and see which lenders fit your needs today.
FAQ
What features make Lending Gurus suitable for business owners looking for quick funding?
Lending Gurus offers a conversational AI advisor named Guru, which allows you to explore funding options without a hard credit pull. This feature facilitates a smooth matching process that keeps your credit score unaffected during the preliminary search. You can engage with the platform to receive personalized lender matches tailored to your specific business needs.
How does Lending Gurus compare to Lendio in terms of speed of approvals?
Lendio is known for its extensive network of more than 75 verified lenders and often provides approval and funding within 24 hours. Lending Gurus, while also effective, primarily shines in delivering tailored matches without impacting your credit score during the exploration phase. This focus on discovery without commitments may suit you better if you want to assess options before formal applications.
Is there a cost associated with using Lending Gurus for business financing?
Applying through Lending Gurus is free for applicants because the platform earns commissions from lender referrals after successful funding. This model allows you to explore your financing options without upfront costs, giving you a risk-free way to discover suitable lenders.
Can I compare offers from multiple lenders with Lending Gurus?
Lending Gurus allows you to receive tailored recommendations for lenders based on your needs, but it does not directly present competing offers like a traditional marketplace. You can discuss options with Guru and make informed decisions based on various lender matches before any commitment.
How does Lending Gurus support businesses with seasonal cash flow needs?
Lending Gurus provides a matching approach that lets you find various types of funding, suitable for businesses facing seasonal fluctuations. By connecting to suitable lenders without a hard credit pull, you can explore options that align with your cash flow requirements without risking your credit score.
