
Yes, you can get an instant decision on a personal loan through many online lenders and matching platforms. That decision typically arrives in minutes using automated underwriting, but it’s almost always preliminary, not a locked-in funding guarantee. The fastest realistic path to cash is same day or next business day, and only if you sign quickly and your documents check out. Start by prequalifying with a soft credit check so you can compare offers before committing to one.
Table of Contents
- Which Lenders Give You an Instant Personal Loan Decision?
- What Does an “Instant Decision” Actually Mean?
- What Do Lenders Check in Seconds, and What Slows Them Down?
- How to Apply for the Fastest Possible Loan Decision
- How Fast Does Money Actually Show Up After Approval?
- What Red Flags Should You Watch for When Chasing Fast Funding?
- How Guru Speeds Up Your Search for a Lender
- When Speed Matters More Than Cost, and When It Doesn’t
- Ready to Start Matching With a Lender?
- Sources
- FAQ
Which Lenders Give You an Instant Personal Loan Decision?
Not every lender moves at the same speed, and knowing which type you’re dealing with saves you from wasted applications during a cash crunch.
Online direct lenders and fintech companies built their entire model around automated underwriting. You fill out a form, connect your bank account or upload pay stubs, and their system checks your identity, income, and credit signals in real time. Many of these platforms return a decision in minutes because there’s no loan officer manually reviewing your file line by line.
Matching services and loan marketplaces work a little differently. Instead of underwriting you directly, they collect your information once and route it to multiple lending partners who can extend prequalified offers, often based on a soft credit pull that won’t dent your score. This is useful when you don’t know which lender fits your situation, since one application can surface several offers at once instead of you filling out five separate forms.
Traditional banks and credit unions have caught up somewhat, offering online prequalification tools of their own. But their systems tend to lean more on manual verification, especially for larger loan amounts or first-time customers, which slows things down.
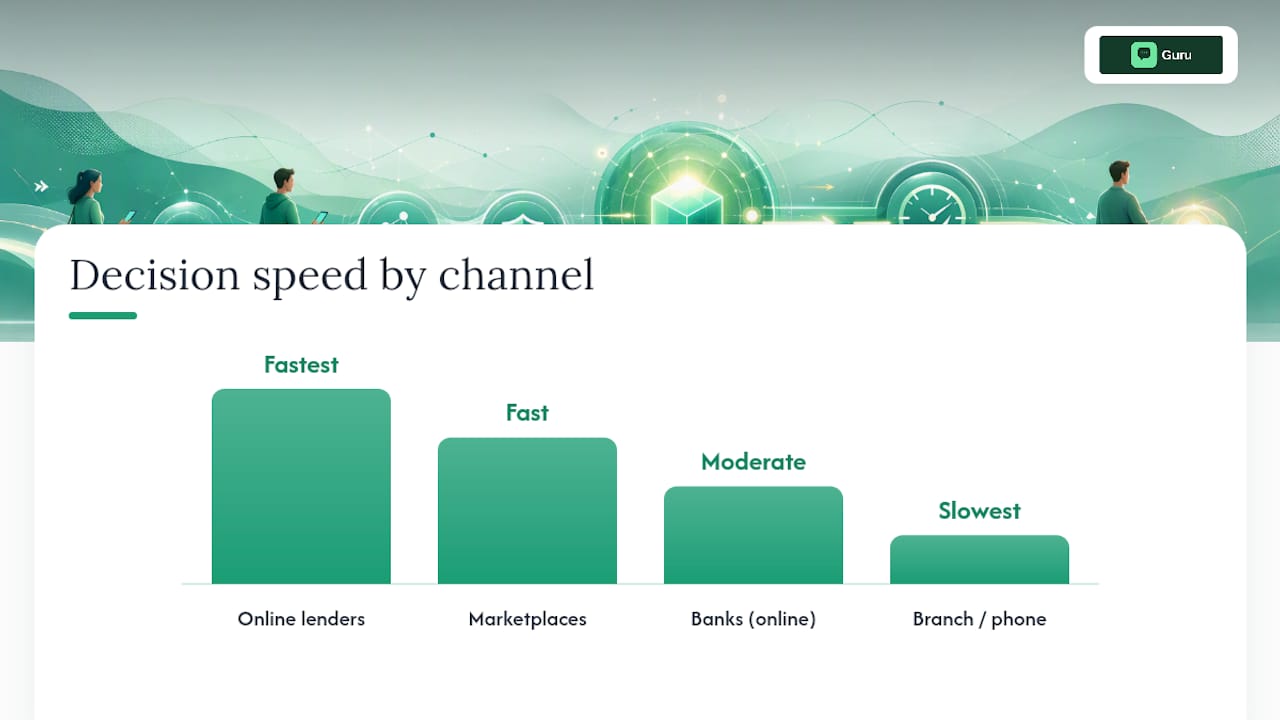
Here’s how the speed typically breaks down by channel:
- Online lenders and fintechs: Fastest for automated decisions; funding often same day or next business day.
- Marketplace or matching tools: Fast for comparing prequalified offers; final funding speed depends on which partner you choose.
- Banks and credit unions (online): Moderate speed; often next day or longer, especially for new customers.
- Branch or phone applications: Slowest option; rarely instant, since a person has to manually process your file.
If speed is your priority, start with an online lender or a matching tool before calling a bank branch.
What Does an “Instant Decision” Actually Mean?
An instant decision is a preliminary approval or denial generated by automated underwriting within seconds or minutes, not a final commitment to fund your loan. Most lenders reach this initial verdict using a soft credit pull, which lets you see potential offers without affecting your credit score.
That’s the good news. The catch is that a hard credit pull and full underwriting usually follow once you accept an offer. At that stage, the lender verifies your identity, income, and bank details against what you submitted. If something doesn’t match, your instant decision can be reversed, downgraded, or delayed even after it looked approved on your screen.
Some lenders describe this candidly: fast approvals are conditional on your data checking out and your bank processing the transfer without issues. The lender, not the instant decision engine, has final say over your actual rate, term, and funding date. Treat the instant result as a strong signal, not a done deal.
What Do Lenders Check in Seconds, and What Slows Them Down?
Automated systems scan a narrow set of data points to reach a fast verdict, and understanding them helps you avoid unnecessary delays.
In those first few seconds, most platforms check your identity against government records, pull a soft credit signal to gauge basic risk, and, if you’ve linked your bank account, scan a snapshot of your income and cash flow. Some also evaluate device and behavior signals, like whether your application pattern resembles known fraud attempts.
Quick fact: Automated underwriting frequently reduces approval decision times but escalates to manual review when bank-sourced income data or identity signals don’t line up cleanly.
A handful of common triggers push your file into manual review, which can add a day or more to your timeline:
- Bank account details that don’t match your stated name or address.
- Large, unexplained deposits that appear right before you applied.
- Income figures on your application that don’t match your bank statements.
- Device or location signals that look inconsistent with your usual activity.
- Uploaded documents that are blurry, incomplete, or don’t match your other entries.
If you suspect a lender is dragging out your approval unfairly or misrepresenting terms, the CFPB’s complaint database lets you search complaint histories for that company before you commit.
How to Apply for the Fastest Possible Loan Decision
Getting an instant decision isn’t luck. It’s mostly about eliminating the friction points that force a system to kick your file into manual review.
- Gather your documents before you start. Have a government-issued ID, your two most recent pay stubs or proof of income, recent bank statements, and your account and routing numbers ready. Bankrate’s guidance on this is blunt: proactive preparation is the single biggest lever you control against verification delays.
- Prequalify with a soft-pull tool first. Comparing offers through a matching platform lets you see likely terms without a hard inquiry hitting your credit report, so you can shop around risk-free before applying formally.
- Fill out every field accurately. A mismatched address, an old employer, or a rounded-up income figure is exactly the kind of inconsistency that flags your file for manual review.
- Choose an instant disbursement method if it’s offered, and eSign your agreement the moment you receive it. Waiting even a few hours can push you past a lender’s daily funding cutoff.
- Apply early in the day, on a business day. Weekend or late-night applications often sit until the next processing window opens.
- Respond immediately to document requests. Use the lender’s secure upload portal rather than email, and check your email or app notifications constantly during the process.
- If you’re denied, read the reason before reapplying anywhere. A quick fix, like updating outdated income info, might be all that’s needed. If the issue is structural, like a debt-to-income ratio that’s too high for that particular lender, try a different lender type or a matching service instead of applying blind.
Pro Tip: Keep digital copies of your last two pay stubs and most recent bank statement saved on your phone before you even start looking for a loan. When a lender asks for verification, you upload in seconds instead of scrambling to find a scanner at 11 p.m.
How Fast Does Money Actually Show Up After Approval?
An instant decision doesn’t mean instant cash. The gap between “approved” and “funded” depends heavily on disbursement method and how quickly you complete your side of the process.
Same-day funding is realistic mainly when you sign before the lender’s daily cutoff and choose a debit-card push transfer, since some lenders design their fastest option specifically around that combination. ACH transfers, the more common default, usually land in your account the next business day. Paper checks or files that require manual document verification can take two or more business days, sometimes longer if anything needs correcting.
| Disbursement method | Typical timeline | Notes |
|---|---|---|
| Debit card push | Same business day (if signed by cutoff) | Fastest option; may carry a small fee |
| ACH bank transfer | Next business day | Most common default method |
| Paper check | 2+ business days | Slowest; adds mailing time |
| Manual review required | 1+ business days minimum | Applies regardless of chosen method |
Once you’re approved, the fastest actions you control are picking the instant push option if it’s offered, double-checking your debit card details, and accepting the offer the moment it’s presented rather than sleeping on it.
What Red Flags Should You Watch for When Chasing Fast Funding?
Urgency makes people skip steps they’d normally catch, and that’s exactly what predatory lenders count on.
Watch for lenders who won’t clearly disclose the APR before you sign, who bundle in mandatory add-on products like insurance you never asked for, or who pressure you to accept an offer within minutes using countdown timers or urgent language. A legitimate lender gives you time to read your agreement.
Fee structures deserve a close look too. Origination fees are common and usually disclosed as a percentage of your loan amount, and instant push transfers sometimes carry a small extra fee compared to standard ACH. Neither is automatically a scam, but both should be spelled out clearly in your loan disclosure, not buried or mentioned only after you’ve signed.
Before accepting any offer, verify the lender is actually licensed using NMLS Consumer Access, the standard lookup for state-licensed lending companies. It only takes a minute, and it’s the difference between borrowing from a real institution and getting caught by an unlicensed operator using a real-sounding name.
- Vague or missing APR disclosure before you sign.
- Required add-on products you didn’t ask for.
- High-pressure countdown timers or urgent callback demands.
- No verifiable license on NMLS Consumer Access.
- Fees that appear only after you’ve already accepted the offer.
How Guru Speeds Up Your Search for a Lender
Guru is a free conversational tool that asks about your situation, your loan amount, and your timeline, then matches you with lending partners who fit. There’s no hard credit pull during that matching process, so you can explore your options without any impact on your credit score.
The practical benefit is fewer wasted applications. Instead of submitting your information to five different lenders and hoping one comes through fast, you go through one intake conversation and get routed toward partners who are more likely to fit your profile, including ones known for quick automated decisions. Guru also flags what documents you’ll likely need up front, so you’re not scrambling once a partner asks for verification.
Lending Gurus doesn’t underwrite your application, set your rate, or guarantee approval or funding timing. Guru is a matching tool, not a lender. Every decision on approval, rate, term, and funding speed belongs to the lending partner you’re matched with.
When Speed Matters More Than Cost, and When It Doesn’t
Speed and cost pull in opposite directions more often than borrowers expect, and the instinct to grab the fastest offer isn’t always the right call.
An instant decision loan makes sense for a genuinely urgent, predictable expense: a car repair you need this week, a medical bill with a hard deadline, a security deposit you’ll lose if you don’t move fast. In those cases, paying slightly more for speed is a reasonable trade.
Where I think people get it backwards is treating every borrowing decision like an emergency. If you’re consolidating debt or financing something with flexibility on timing, slowing down to compare two or three prequalified offers side by side, rather than accepting the first instant approval, usually saves real money over the life of the loan. The rate difference between a rushed decision and a compared one can be significant, and a few extra hours of shopping rarely costs you the loan itself.
My rule of thumb: if you can wait even one day, prequalify with at least two sources before signing anything. If you genuinely can’t wait, understand you’re paying a premium for that speed, and go into it with your eyes open.
— Chris
Ready to Start Matching With a Lender?
You’ve already covered a lot of ground here on documents, disbursement methods, and red flags to avoid. Here’s the direct next step: Lending Gurus gives you one place to compare lending partners instead of hunting through five separate applications on five separate sites.

Guru asks a few questions about your situation and timeline, matches you with vetted lending partners, and does it without a hard credit pull during the matching process. You stay in control of every decision, and the partners you’re matched with are the ones who decide on approval, rate, and funding speed, not Guru. If speed is what you need right now, this cuts out the repetitive paperwork that eats up your time. Read more about how Lending Gurus works, or check the terms and conditions before you start, then begin your match to see which lending partners fit your situation today.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- How do same-day loans work? | Experian
- Documents required for personal loan | Bankrate
- Consumer complaint database | CFPB
- NMLS Consumer Access
FAQ
What Is the Easiest Loan to Get Approved For Quickly?
Personal loans from online lenders using automated underwriting tend to be the fastest to get an instant decision on, especially if your income and identity documents are ready to upload immediately.
How Can I Get a Personal Loan Immediately?
Prequalify through an online lender or a matching tool like Guru using a soft credit check, have your ID, pay stubs, and bank statements ready, and sign your agreement the moment an offer arrives to hit same-day funding cutoffs.
Which Loan Can I Get Approved For the Fastest?
Small, short-term personal loans through fintech lenders with automated underwriting typically produce the fastest instant decisions, though your actual approval depends on your income, credit signals, and the specific lender’s criteria.
Who Will Approve a Loan When Other Lenders Have Turned Me Down?
No lender can promise approval regardless of your financial profile, but a matching service that checks multiple partners at once, without a hard credit pull, gives you a broader shot at finding one whose criteria fit your situation.
Can an Instant Decision Be Reversed Later?
Yes. An instant decision is a preliminary result, and it can change if your identity, income, or bank details don’t match what you submitted during final verification.
