
TL;DR:
- Fast business funding options include merchant cash advances and ACH revenue loans, which can fund within hours or days. Using lender matching services like Lending Gurus reduces application time and avoids multiple credit inquiries by surfacing suitable offers quickly. Borrowers should prepare key documents and ask questions about total repayment and fees to avoid costly red flags.
Revenue-first products — merchant cash advances, ACH revenue loans, and short working capital loans — are the fastest route to funding for most small businesses right now. Pair one of those products with a lender matching service, and you can surface multiple offers in a single session instead of filling out five separate applications.
Realistic timelines to know before you apply:
- Same day: Possible for qualified applicants who submit complete documents before noon Eastern and sign by early afternoon
- 24 hours: Achievable for some applicants with rapid verification and all documents in place
- 24–72 hours: The most common funding window for qualified applicants across most fast products
- 2–5 business days: Typical for short-term term loans and some lines of credit that require additional verification
Timeline caveat: Same-day funding is possible but rarely guaranteed. Most qualified applicants receive decisions the same day and funding in 24–72 hours. Some lenders, like those linked to payments platforms, may fund as fast as the next business day.
The single best first action: use a matching tool like Guru (Lending Gurus’ free intake advisor) to surface matched lender options quickly, without a hard credit pull. Your FICO score is a factor lenders weigh, but monthly revenue and cash flow carry more weight in fast underwriting decisions.
Table of Contents
- What are the fastest business loan options right now?
- How do you pick the fastest loan without getting burned?
- What does “fast” actually mean for business funding?
- How we picked these fast funding options
- Why Lending Gurus can speed up your search for fast funding
- When should you use a matching service vs. applying direct?
- Lending Gurus matches you to fast lenders in minutes
What are the fastest business loan options right now?
The table below covers the main product categories you’ll encounter when you need quick business funding. Costs, timelines, and eligibility signals vary by lender and your specific profile — treat these as typical ranges, not guarantees.
| Product Type | Typical Time to Funding | Best For | Loan Amounts (typical) | Min. Eligibility Signals | Cost Structure | Documents Usually Required |
|---|---|---|---|---|---|---|
| Merchant Cash Advance (MCA) | Same day–24 hours | High card-volume businesses needing immediate cash | Varies by lender | 4+ months in business with modest monthly revenue | Factor rate; daily/weekly remittance | Bank statements, merchant processing statements |
| ACH Revenue Loan | Decisions in hours, funding in 24 hours or less | Businesses with consistent bank deposits | Varies based on lender | At least several months in business with steady revenue | Factor rate or fixed fee; daily/weekly ACH withdrawals | Bank statements, voided business check |
| Short-Term Working Capital Loan | 24–72 hours | Covering gaps, payroll, inventory | Typical ranges vary | At least a few months in business with some credit history | May have higher APR than traditional loans; fixed term | Bank statements, photo ID, basic business info |
| Invoice Financing | 24–48 hours | B2B businesses with outstanding invoices | Advances a substantial portion of invoice value | Active receivables and months in business required | Factoring fee; varies by aging | Invoices, customer contact info, bank statements |
| Fast Line of Credit | 24–72 hours for initial approval; subsequent draws may be same day | Ongoing working capital needs | Loan amount varies by provider | Typically requires several months in business, credit history | Variable draw fees or interest on amount drawn | Bank statements, basic business financials |
| Platform-Linked Financing | Next business day or faster | Businesses already using a payments platform | Varies by platform history | Active account + transaction history on platform | Varies; often fixed fee | Minimal — eligibility pre-verified via platform data |
Lender matching services like Lending Gurus sit above all of these. You submit one intake, and the platform surfaces matched partner options across product types. Lending Gurus does not set rates, approve loans, or guarantee timelines — those decisions belong to the partner lenders. What the matching approach does is cut the time you spend hunting for the right product.
Note on hard pulls: Some lenders run a hard credit inquiry before issuing a formal offer. Ask before you authorize any credit check. Lending Gurus’ Guru intake uses a soft prequalification that does not affect your credit score.
Pro Tip: If your business already processes payments through a major fintech or payments platform, check that platform first. Platform-linked products can fund next-business-day or faster because your transaction history is already verified — no bank statement upload required.
How do you pick the fastest loan without getting burned?
Speed matters, but signing the wrong product can cost you more than the delay would have. Work through this checklist before you commit.
Start with your purpose
- Emergency cash gap (payroll due tomorrow, supplier invoice overdue): MCA or ACH revenue loan — fastest to fund, no collateral required.
- Planned purchase (equipment, inventory reorder): Short-term working capital loan or equipment financing — slightly slower but structured repayment fits a defined asset.
- Ongoing working capital (seasonal swings, recurring shortfalls): Fast line of credit — draw only what you need, pay interest on the drawn amount.
- Outstanding invoices slowing cash flow: Invoice financing — converts receivables to cash without taking on new debt.
Documents to have ready before you apply
- Three to six months of business bank statements (most fast lenders require this as their primary underwriting input)
- Voided business check (for ACH setup)
- Government-issued photo ID
- Basic business info: legal name, EIN, time in business, monthly revenue estimate
- Merchant processing statements (required for MCAs)
Questions to ask any fast lender before you sign
- What is the total repayment amount, not just the factor rate or fee?
- How and when do you initiate the first withdrawal?
- Is there a prepayment discount, and how is it calculated?
- What happens if a payment fails — is there a grace period or an immediate penalty?
- Will you run a hard credit pull before issuing the final offer?
Red flags to avoid
- Lenders who cannot or will not state the total repayment amount upfront
- Mandatory daily ACH withdrawals with no stated cap or adjustment process
- Origination or processing fees that appear only in the fine print after you’ve applied
- Any lender that asks for payment before funding is deposited in your account
What does “fast” actually mean for business funding?
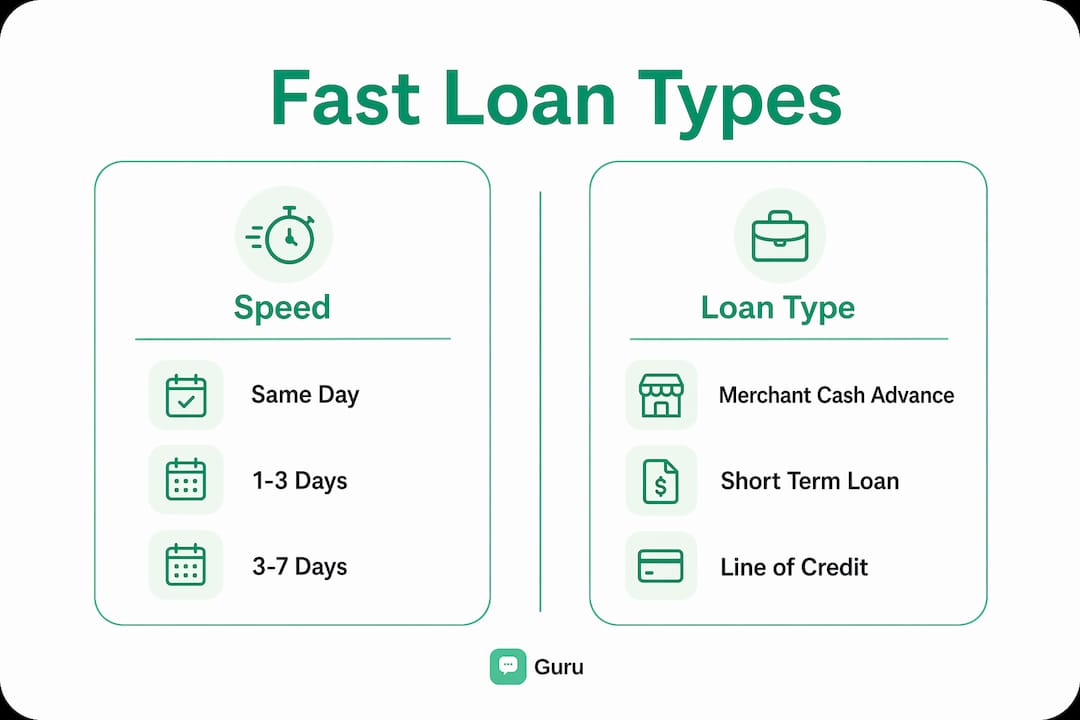
“Fast” in business lending covers a wide range of products, each with different underwriting logic and realistic timelines. Knowing which product you’re looking at tells you what to expect.
The main fast product types
Merchant cash advances (MCAs) are advances against future card or revenue receipts. Lenders look at your merchant processing volume and recent bank deposits rather than multi-year financials. Repayment comes as a percentage of daily sales or fixed daily/weekly ACH draws. Same-day funding is possible for strong applicants.
ACH revenue loans work similarly but focus on total bank deposit patterns rather than card volume specifically. Revenue-based underwriting that reviews recent bank deposits allows decisions in as little as 2 hours, and funding may occur in 4–24 hours for qualified applicants who submit complete documents.
Short working capital loans are fixed-term loans with set repayment schedules. They take slightly longer — typically 24–72 hours — because lenders verify a few more data points, but they offer more predictable repayment than MCAs.
Invoice financing converts outstanding invoices to immediate cash. The lender advances a percentage of the invoice value (often 85–90%) and collects when your customer pays. Timeline is typically 24–48 hours once invoices are verified.
Fast lines of credit give you a revolving credit limit you draw from as needed. Initial approval takes 24–72 hours; subsequent draws may be same day once the line is established.
Why timelines vary
Lenders’ published speed claims vary; actual funding depends on verification completeness and bank ACH windows. A complete application submitted at 8 AM funds faster than an incomplete one submitted at 3 PM. ACH batches have cutoff times — miss the cutoff and your funds arrive the next business day.
Pro Tip: Submitting before noon Eastern and signing your agreement by early afternoon gives you the best shot at same-day ACH funding. Many lenders initiate same-day transfers only for applications completed before their early-afternoon cutoff.
The speed-cost tradeoff
Fast products trade speed for cost. MCAs and short working capital loans typically carry higher effective costs than conventional bank loans. That premium is the price of skipping the weeks-long underwriting process. Use these products for short-term gaps, not long-term financing needs.
| Product | Typical Funding Speed | Relative Cost | Repayment Predictability |
|---|---|---|---|
| MCA | Same day–24 hours | Highest | Variable (% of sales) |
| ACH Revenue Loan | 24–48 hours | High | Fixed daily/weekly |
| Short-Term Working Capital | 24–72 hours | Moderate–High | Fixed term |
| Invoice Financing | 24–48 hours | Moderate | Tied to invoice payment |
| Fast Line of Credit | 24–72 hours (initial) | Moderate | Draw-based |
How we picked these fast funding options
Selecting which product types and providers to highlight came down to five criteria.
- Speed potential: Does the product type genuinely fund within 24–72 hours for qualified applicants, based on published lender claims and industry reporting?
- Qualification transparency: Are the minimum eligibility signals (revenue, time in business, credit) clearly stated so you can self-screen before applying?
- Product variety for rapid needs: Does the option cover the range of urgent situations — emergency gaps, invoice delays, equipment needs?
- Minimum documentation: Can a qualified applicant complete the process with bank statements and basic business info, without multi-year audited financials?
- Application experience: Is the process genuinely fast, or does “fast” apply only to the decision while funding takes days longer?
Data sources include lender-published speed claims, industry reporting on funding timelines, and product page review across multiple fast-funding providers.
Approval disclaimer: Lending Gurus matches your profile to vetted lending partners. Partners decide approvals, amounts, rates, and timelines. No approval or specific funding window is guaranteed. The options above represent product categories, not a guarantee that any individual applicant will qualify or fund within the stated timeframes.
Why Lending Gurus can speed up your search for fast funding
Finding the right lender fast is its own problem. Applying to five lenders separately means five applications, five sets of documents, and five separate credit inquiries if you’re not careful. Using a matching service reduces the time you spend applying to multiple lenders and can surface offers faster than applying to each provider separately.
Here’s how Lending Gurus works:
- Guru intake: Answer a short set of questions through Guru, the platform’s conversational advisor. No hard credit pull at this stage.
- Matched partner options: Lending Gurus matches your profile to vetted lending partners whose products fit your situation — revenue level, time in business, funding need.
- Partner follow-up: You choose which partner to connect with. The partner then runs their own verification and approval process. Lending Gurus does not set rates, approve loans, or control funding timelines.
Platform features that help you move faster:
- Single intake instead of multiple separate applications
- Soft prequalification that protects your credit score during the search phase
- Matched partners filtered to your profile, so you’re not wasting time on products you won’t qualify for
- Transparent next steps — you know what happens after you connect with a partner
What Lending Gurus does and doesn’t do: Lending Gurus is a matching platform, not a lender or broker. Guru surfaces options; partners make the lending decisions. There are no guaranteed approvals, no promised rates, and no committed funding timelines. What you get is a faster, cleaner search process.
When should you use a matching service vs. applying direct?
The honest answer depends on how well you know the market and how much time you have.
If you already have a relationship with a lender and you know their terms, applying direct is fine. You skip the matching step and go straight to the application. That works when you have a preferred lender, you’ve borrowed from them before, and you know you qualify.
Use a matching service when you’re unfamiliar with the fast-funding market, when you need to compare multiple product types quickly, or when you’re not sure which product fits your situation. The matching step adds a few minutes upfront but saves you from applying to lenders whose products don’t fit your revenue level or time in business.
Before any application, have these ready:
- Your three most recent months of business bank statements (six months is better)
- A voided business check
- Your EIN and basic business registration info
- A rough monthly revenue figure — lenders will verify this, but having it ready speeds the intake
After you receive funding, the work isn’t over. Set up a repayment calendar the day you receive funds. Daily or weekly ACH withdrawals can catch you off guard if your cash flow dips. Monitor your bank balance against your scheduled withdrawals, and contact your lender immediately if you anticipate a shortfall — most lenders have hardship or modification options, but only if you ask before you miss a payment. Defaulting on a fast business loan can trigger personal guarantee clauses and damage both your business and personal credit.
Lending Gurus matches you to fast lenders in minutes
Spending hours researching lenders when you need funding quickly defeats the purpose. Lending Gurus gives you a faster path: one short intake through Guru, matched partner options based on your actual profile, and a clear next step — all without a hard credit pull.

The process is free and non-binding. You’re not committed to anything until you choose to move forward with a partner. Here’s what to expect:
- Quick intake: Guru asks about your business, funding need, and monthly revenue — takes a few minutes.
- Matched offers: Lending Gurus surfaces vetted partners whose products fit your profile.
- Partner process: Your chosen partner handles verification, approval, and funding. They set the rates and terms.
- Soft prequalification: Your credit score is not impacted during the Lending Gurus matching phase.
Partners decide approvals and timelines — Lending Gurus does not guarantee funding or specific rates. What it does is cut the search time significantly so you can focus on the lender conversation that actually matters.
Start your intake at Lending Gurus and see which partners match your profile today. For a full walkthrough of the process, visit the how it works page.
This article is general information, not financial or legal advice. Confirm current eligibility requirements and terms directly with any lender before proceeding.
