
A business checking account is a bank account designed specifically to manage a company’s income, expenses, and cash flow separately from personal finances. Understanding the difference between business vs personal checking is not just a bookkeeping preference. It affects your legal protection, tax compliance, and ability to access financing. Whether you are a freelancer, a sole proprietor, or running an LLC, the account type you choose has real consequences.
1. What sets business vs personal checking accounts apart?
Business checking accounts and personal checking accounts serve fundamentally different purposes. A personal checking account handles individual daily transactions: paying bills, receiving a paycheck, and managing household spending. A business checking account manages revenue, vendor payments, payroll, and operating expenses for a company.
The distinction matters beyond labeling. Business accounts establish a professional financial history that personal accounts cannot replicate. That history becomes critical when you apply for a business loan or line of credit. Banks and lenders evaluate your business finances separately from your personal finances, and they expect to see dedicated records.
Personal accounts also carry usage restrictions most owners overlook. Many banks explicitly prohibit using a personal account for commercial activity. Violating that policy can result in account closure without warning.
2. What are the legal and tax requirements for business banking?
No federal law requires sole proprietors to open a separate business checking account. LLCs, corporations, and partnerships, however, must maintain separate accounts to preserve their liability protections. This is not optional for those entities. It is a condition of the legal structure itself.
The core risk for LLCs and corporations is called piercing the corporate veil. Courts may expose personal assets when personal and business funds are commingled. That means a creditor or plaintiff could reach your personal savings, home equity, or other assets if you have not maintained clean separation. The entire point of forming an LLC or corporation is to limit personal liability, and mixing funds destroys that protection.
For tax purposes, the IRS looks for spending patterns inconsistent with business activity. Mixing personal expenses on a business account triggers audit risk and can invalidate legitimate deductions. A dedicated business account creates a clean audit trail that protects you if the IRS questions your returns.
Key legal risks of mixing funds:
- Loss of corporate veil protection for LLCs and corporations
- Increased IRS audit exposure and potential disallowance of deductions
- Difficulty proving business legitimacy in court or during an audit
- Risk of account closure if a bank identifies prohibited commercial use of a personal account
Pro Tip: Document every transfer between your personal and business accounts as either an owner draw or a capital contribution. Careful documentation of those transfers is essential to maintain formal separation and satisfy both IRS and court standards.
Understanding payment compliance risks is equally relevant here, especially as your business grows and transaction volumes increase.
3. How do operational features differ between account types?
Business accounts offer higher transaction limits and merchant services that personal accounts do not provide. Daily ACH and wire transfer limits are substantially greater, which matters when you are paying vendors, running payroll, or receiving large client payments. Personal accounts cap these limits at levels suited for household use, not business operations.
The feature gap goes further than transaction volume. Business accounts typically include:
- Merchant services for accepting credit and debit card payments
- Payroll processing integrations
- Automated invoicing tools
- Bookkeeping software compatibility (such as QuickBooks or Xero)
- Multiple authorized signers and employee debit cards
Personal accounts rarely offer these features, and when they do, the functionality is limited.
Fee structures differ significantly. Business checking fees range from $15 to $50 monthly, often with minimum balance requirements to waive them. Personal accounts frequently offer no-fee options at lower balance thresholds. Some digital business accounts now offer no monthly fees with advanced features like automated invoice management and 24/7 support, which narrows the cost gap for startups and freelancers.
Business accounts also charge fees for transactions exceeding monthly limits, cash deposits above set thresholds, and wire transfers. If your business handles significant cash volume, factor those fees into your account selection.
Pro Tip: Match your account tier to your actual transaction volume. Paying for a premium business account when you process fewer than 50 transactions per month is unnecessary. Start with a basic tier and upgrade as your volume grows.
4. How does your account type affect credit building and financing?
A business checking account builds a financial history that lenders evaluate separately from your personal credit profile. This separation is the foundation of business credit. Without it, lenders have no business-specific data to assess, and your personal credit score carries the entire weight of any financing decision.
Lenders prefer business financial data kept separate from personal accounts when evaluating loan applications. A dedicated account demonstrates that your business operates as a real, organized enterprise. That perception directly affects approval odds and loan terms.
The credit-building benefits of a dedicated business account include:
- Establishing a business banking relationship that supports future credit line applications
- Providing lenders with clean revenue and cash flow records
- Supporting applications for SBA loans, equipment financing, and business lines of credit
- Demonstrating consistent business activity to credit bureaus that track commercial accounts
One important limit to understand: personal guarantees are commonly required for SBA and commercial loans even when you have established business credit. Owners with 20% or more equity typically must sign unlimited personal guarantees. A business account reduces your exposure in many situations, but it does not eliminate personal liability on most small business loans.
5. When should you open a business checking account?
The right time to open a business checking account depends on your business structure and goals. The guidance below breaks down the decision by entity type.
Sole proprietors: Opening a business account is not legally required, but it is strongly recommended. A business account creates a clean audit trail that saves significant administrative time during tax season, even for freelancers. The primary value for sole proprietors is administrative efficiency and tax season simplicity, not legal obligation.
LLCs and corporations: A dedicated business account is effectively mandatory. Maintaining separate accounts is key evidence for the IRS and courts verifying legitimate business activity. Skipping this step puts your liability protection at risk from day one.
Startups and cash-heavy businesses: Weigh the fee structure carefully. Some digital business accounts now offer no monthly fees with features like automated invoicing, which makes the cost argument for delaying a non-issue.
When opening a business account, banks require government ID and a Social Security number to comply with Know Your Customer (KYC) regulations, even when your business has an EIN. Banks verify the identity of all authorized signers regardless of entity type. Prepare your EIN, formation documents, and ownership information before you apply.
| Business type | Business account required? | Primary reason |
|---|---|---|
| Sole proprietor | Recommended, not required | Tax clarity and audit trail |
| LLC | Yes | Preserve corporate veil protection |
| Corporation | Yes | Legal compliance and liability |
| Partnership | Yes | Separation of partner contributions |
Consider these factors when selecting an account:
- Monthly fee and minimum balance requirements
- Transaction volume limits and overage fees
- Cash deposit handling and associated costs
- Bookkeeping software compatibility
- Online banking features versus branch access needs
Key Takeaways
Business checking accounts are legally required for LLCs and corporations, and practically necessary for any business owner who wants clean tax records, liability protection, and access to financing.
| Point | Details |
|---|---|
| Legal separation matters | LLCs and corporations must keep funds separate to preserve personal liability protection. |
| Sole proprietors benefit too | A dedicated account simplifies tax filing and reduces audit risk even without a legal mandate. |
| Fee structures vary widely | Business account fees range from $15 to $50 monthly; digital options can reduce or eliminate this cost. |
| Credit building requires separation | Lenders evaluate business financial history separately, making a dedicated account foundational for financing. |
| Personal guarantees still apply | Even with a business account, SBA and commercial loans typically require a personal guarantee from owners with 20%+ equity. |
Why I think most small business owners wait too long on this
The most common mistake I see small business owners make is treating a business checking account as something to set up “once things get serious.” By the time they open one, they have months of mixed transactions to untangle, deductions they cannot prove, and a tax season that costs them hours they did not budget for.
The cost argument for waiting does not hold up. Digital business accounts with no monthly fees exist right now. The idea that a business account is expensive is outdated. What is expensive is reconstructing six months of mixed personal and business transactions when your accountant charges by the hour.
The liability argument is even clearer. If you have an LLC and you are running business income through your personal account, you are paying for legal protection you are not actually receiving. Courts do not care that you intended to keep things separate. They look at what you actually did.
My honest recommendation: open a business account the same week you register your business. The upfront time investment is minimal. The protection and clarity you gain from day one are worth far more than the convenience of waiting.
— Chris
Lending Gurus and your next step in business financing
Once your business banking is in place, the next question most owners face is funding. Whether you need working capital, equipment financing, or a line of credit, having a dedicated business account already puts you ahead of most applicants.
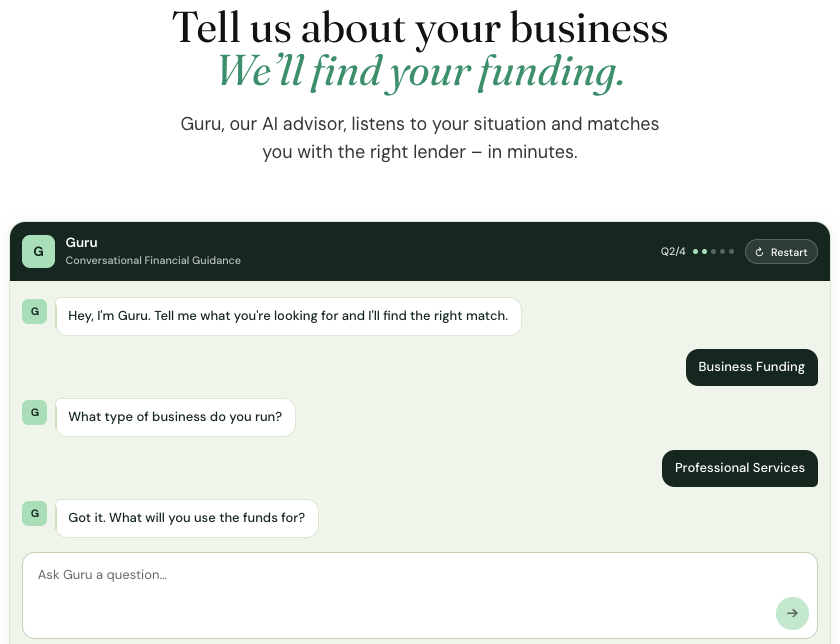
Lending Gurus connects small business owners with suitable lenders in minutes through an AI-powered process that requires no hard credit pull. The platform’s conversational advisor, Guru, listens to your specific situation and matches you with financing options that fit. You can see how it works and get matched without the paperwork and delays of traditional bank applications. When you are ready to put your business banking foundation to work, Lending Gurus makes the financing step straightforward.
FAQ
Do I need a business checking account as a sole proprietor?
No federal law requires sole proprietors to open a separate business account, but doing so creates a clean audit trail and simplifies tax filing significantly. Most accountants strongly recommend it.
Can I use a personal account for my LLC?
Using a personal account for an LLC puts your liability protection at risk. Courts can pierce the corporate veil and expose your personal assets if business and personal funds are commingled.
What documents do I need to open a business checking account?
Banks require government-issued ID, a Social Security number, your EIN, and business formation documents. KYC regulations require identity verification for all authorized signers.
How does a business checking account help me get a loan?
A dedicated business account builds a separate financial history that lenders use to evaluate your business. It demonstrates organized operations and provides the clean cash flow records lenders require for most business loan applications.
What fees should I expect with a business checking account?
Business checking fees typically range from $15 to $50 per month, with additional charges for excess transactions, cash deposits, and wire transfers. Some digital business accounts offer no monthly fees with comparable features.
